Why Electric Car Owners Pay Up to 25 Percent More for Insurance Than Petrol Drivers
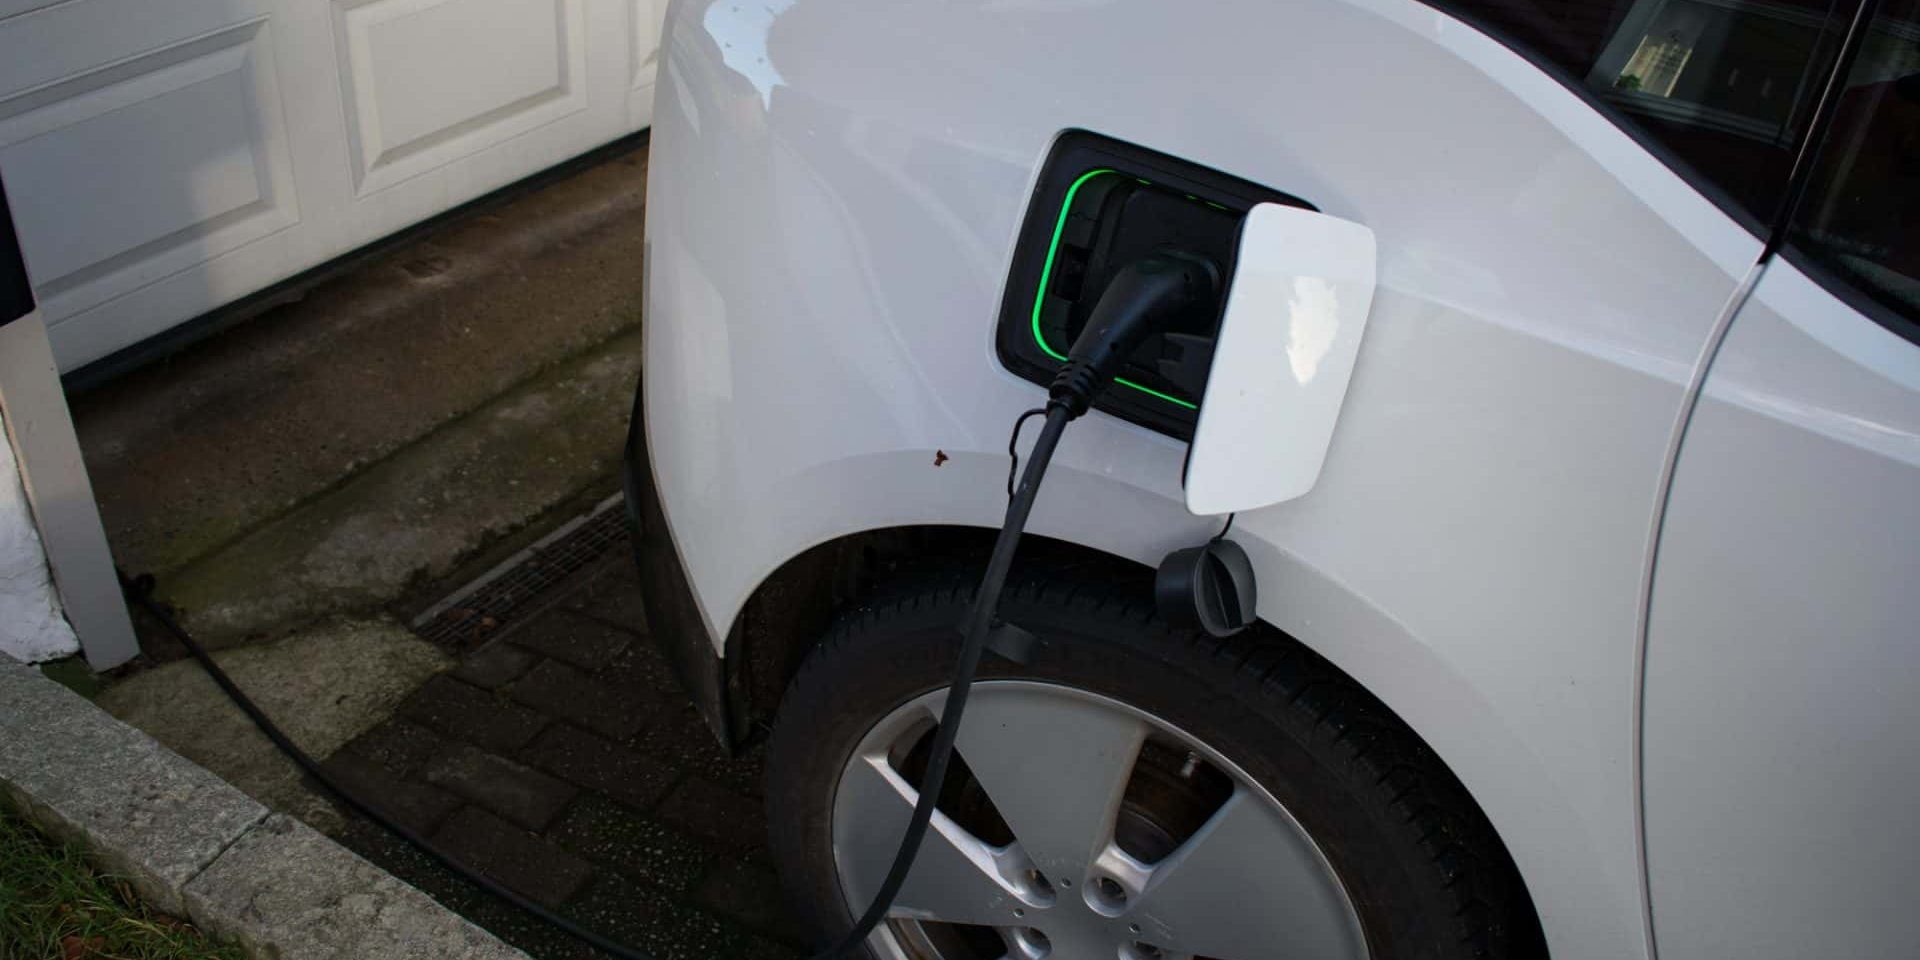

Drivers who have switched to electric cars are paying on average 25 percent more for their motor insurance than they would pay for equivalent petrol models, according to data compiled from comparison site pricing and insurer disclosed figures. For some of the most popular electric vehicles on UK roads, the gap is wider still. Owners of certain models have reported premiums running 30 to 40 percent above the petrol or hybrid equivalents they previously drove.
The premium gap reflects real underlying cost differences rather than arbitrary pricing by insurers. Claims for electric vehicles cost more to settle, take longer to resolve, and produce a higher proportion of total loss outcomes than equivalent internal combustion engine claims. Until those structural cost differences narrow, the insurance pricing will follow.
Understanding why the gap exists, and what, if anything, can be done about it, has become an urgent question for the growing number of UK drivers who have made or are considering the switch to electric.
Why EV Claims Cost More to Settle
The most significant single driver of the cost gap is battery repair and replacement. In a conventional vehicle, the most expensive components involved in a collision are the engine, gearbox, and bodywork. In an electric vehicle, the battery pack typically represents 30 to 50 percent of the vehicle’s total value and is located in the floor of the car, where it is particularly exposed to impact damage in many types of collision, including kerbing incidents and low-speed frontal impacts.
When a battery is involved in a collision, the insurance and repair industry faces a problem that does not exist with conventional engines. Internal damage to lithium-ion cells is not always visible externally and cannot be fully assessed without disassembly or specialist diagnostic equipment. An EV battery pack that appears cosmetically intact after a collision may contain compromised cells that present a fire risk or will degrade significantly faster than expected. Because insurers cannot guarantee the safety or future performance of a repaired battery, many instruct their approved repairers to treat battery damage conservatively, often writing vehicles off rather than authorising speculative repair.
The result is a total loss rate for EVs that is meaningfully higher than for petrol equivalents. Industry figures suggest that EVs are written off at roughly twice the rate of petrol cars in terms of the proportion of claims that result in a total loss, though this varies by vehicle age and model. Each total loss claim is settled at the market value of the vehicle, and EVs carry significantly higher purchase prices than petrol equivalents, making each total loss more expensive to settle.
Labour, Training, and Approved Repairer Scarcity
Even where a repair is possible, the cost is higher than a comparable petrol repair. Working on a high-voltage battery system requires technicians who hold specific qualifications, and the number of such technicians in the UK workforce remains limited relative to the growth of the EV fleet. Approved EV repairers are concentrated in urban areas and some vehicles, particularly those from manufacturers with smaller dealer networks in the UK, may need to travel significant distances to reach a facility authorised to work on them.
The shortage of approved repairers has two direct effects on insurance costs. First, it limits competition for repair work, which keeps labour rates higher than they would be in a fully competitive market. Second, it extends repair times, increasing the period for which the insurer must provide a courtesy vehicle. Courtesy vehicle costs for longer EV repairs are substantial, and some insurers have found that the total hire costs associated with an EV claim can exceed the repair cost itself for lengthy repairs involving specialist battery diagnostics.
Parts supply chains for EVs remain more fragile than those for petrol vehicles in the UK repair market. Manufacturers supply parts directly through their dealer networks rather than through the wider aftermarket parts trade that services petrol vehicles, and some parts have lead times of weeks rather than days. Each additional week in the repair process adds to the total claim cost.
Which Models Have the Biggest Insurance Premium Gap
The premium gap is not uniform across all electric vehicles. It varies by manufacturer, model, and the maturity of the repair ecosystem around each car. Models from established manufacturers with large dealer networks and more developed parts supply chains tend to show smaller gaps than models from newer entrants to the market.
Tesla vehicles have historically attracted some of the largest premium gaps relative to petrol equivalents, driven partly by proprietary parts supply arrangements and the insistence on repair at Tesla-approved centres. The Model 3 and Model Y, which together represent a significant proportion of the UK EV fleet, have seen premiums that were routinely 30 percent or more above equivalent petrol estate and saloon models. Tesla has introduced direct insurance in some markets, though not yet in the UK, as a response to the pricing challenge.
Vehicles from established European manufacturers, including Volkswagen’s ID range and the Renault Zoe, tend to show smaller gaps because the manufacturer’s existing dealer repair network is already approved and equipped for EV work. Even for these vehicles, however, the cost of battery diagnostics and the higher total loss rate keep premiums above petrol equivalents.
What Insurers Are Doing
The insurance industry has invested significantly in developing EV-specific repair capacity. Several insurers have partnered directly with vehicle manufacturers to train and certify approved repairers, and the number of EV-capable body shops in the UK has grown substantially over the past three years. The ABI has published guidance for its members on EV claims handling and has called for greater standardisation in battery diagnostic procedures.
Some insurers have introduced EV-specific policy features designed to reflect the particular risk profile of electric vehicles, including enhanced battery cover, guaranteed replacement vehicle cover during extended repairs, and specific provisions for home charging equipment. These features add value for EV owners but do not reduce the premium gap, because they address specific EV risks rather than reducing the underlying claims cost.
Specialist EV insurers have entered the UK market offering policies tailored to electric vehicle owners, though market share remains small. Their competitive advantage is claimed expertise in managing EV claims efficiently, reducing the cost of claims handling and the length of repair cycles. Whether this expertise translates into meaningfully lower premiums for the customer is something to assess on a model-by-model basis using comparison tools.
Practical Steps for EV Owners Facing High Premiums
EV owners can take several steps to reduce their premiums. The most important is to shop around at every renewal using a comparison site that includes EV-specialist insurers alongside mainstream providers. Comparison sites have improved their EV coverage significantly in recent years and are now a reasonable starting point for most models.
When comparing policies, pay close attention to battery cover terms. Cheaper policies may exclude battery damage not caused by a collision, or may include provisions allowing the insurer to offer a replacement battery rather than a like-for-like settlement in the event of a total loss. If you have financed your vehicle on a PCP or HP agreement, gap insurance deserves consideration, as the difference between an insurer’s market value settlement and the outstanding finance balance can be substantial given current EV depreciation patterns.
Telematics policies are available for EV owners and can produce meaningful savings for drivers with demonstrably safe driving records. Unlike traditional black box policies with wired devices, most modern telematics systems for EVs use smartphone apps or plug-in OBD devices and are straightforward to install. If you drive fewer than 7,000 miles per year, a mileage-based policy may also produce savings relative to a standard annual policy.
Increasing your voluntary excess reduces your headline premium but increases your out-of-pocket exposure in the event of a claim. Given the higher average repair costs for EVs, choose an excess level that you could genuinely afford to pay without financial difficulty, rather than simply selecting the highest available excess to minimise the quoted premium.
What Needs to Change for the Gap to Narrow
The insurance premium gap between EVs and petrol vehicles will narrow as the repair ecosystem matures, but the pace of that convergence depends on several factors that are not fully within the industry’s control.
Battery repairability is the key technical challenge. Where individual battery cells or modules can be assessed, replaced, and certified rather than requiring whole-pack replacement, repair costs will fall and total loss rates will decline. Progress is being made: some manufacturers have moved to more modular battery designs that support cell-level repair, and the independent aftermarket battery repair sector is growing. But certification standards for repaired batteries need to be established and trusted before insurers will routinely authorise cell-level battery repairs rather than writing vehicles off.
The government’s commitment to expanding the public charging network will eventually also help reduce roadside breakdowns, which represent a separate insurance and recovery cost associated with range anxiety-related incidents. More charging infrastructure reduces the likelihood of drivers being stranded and the cost of recovery operations.
For drivers making the switch now, the premium gap is a real additional cost that belongs in any total cost of ownership calculation alongside energy costs, road tax, and maintenance savings. It does not negate the overall economics of electric driving for most buyers, but it reduces the financial advantage, particularly in the first years of ownership when the premium gap tends to be widest.
Sources:

Leave a Comment
More in News

What to Do if Your Car Overheats on the Motorway Before the Engine Fails
DVSA’s New Waiting Time Measure Shows 9.7 Weeks, Not the 21.8 Learners Were Told
Every Illegal Tyre Now Risks Drivers a £2,500 Fine and Three Penalty Points

Every Driver Ignores This Dashboard Light and It Costs Them Their MOT
What the New GOV.UK Wallet Means for Every UK Driver This Year
Trending on Motoring Chronicle

Roof Rack Fines Can Reach £2,500 as Holiday Drivers Ignore Safety Checks

Walmart’s EV Charging Network Quietly Becomes One of the Nation’s Largest
Annapolis Speed Cameras Go 24/7 Starting September 8, With Fines Up to $425
Special livery package for 911 GT3 celebrates 50th anniversary of ANDIAL [Photo Gallery]