
Car Insurance Set to Hit $2,242 a Year as 32 States See Hikes
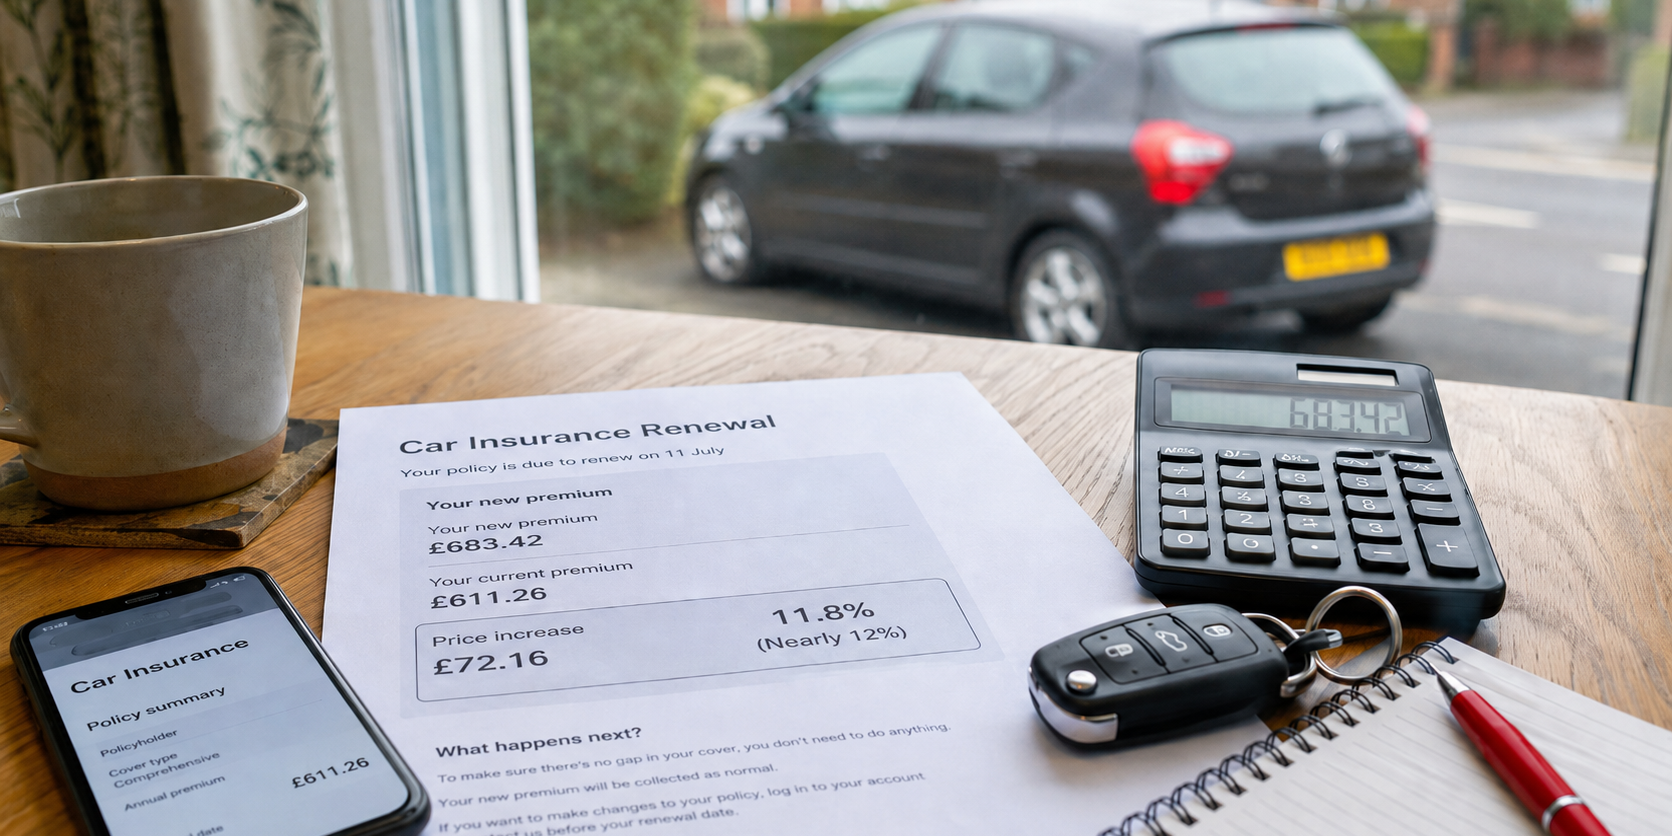
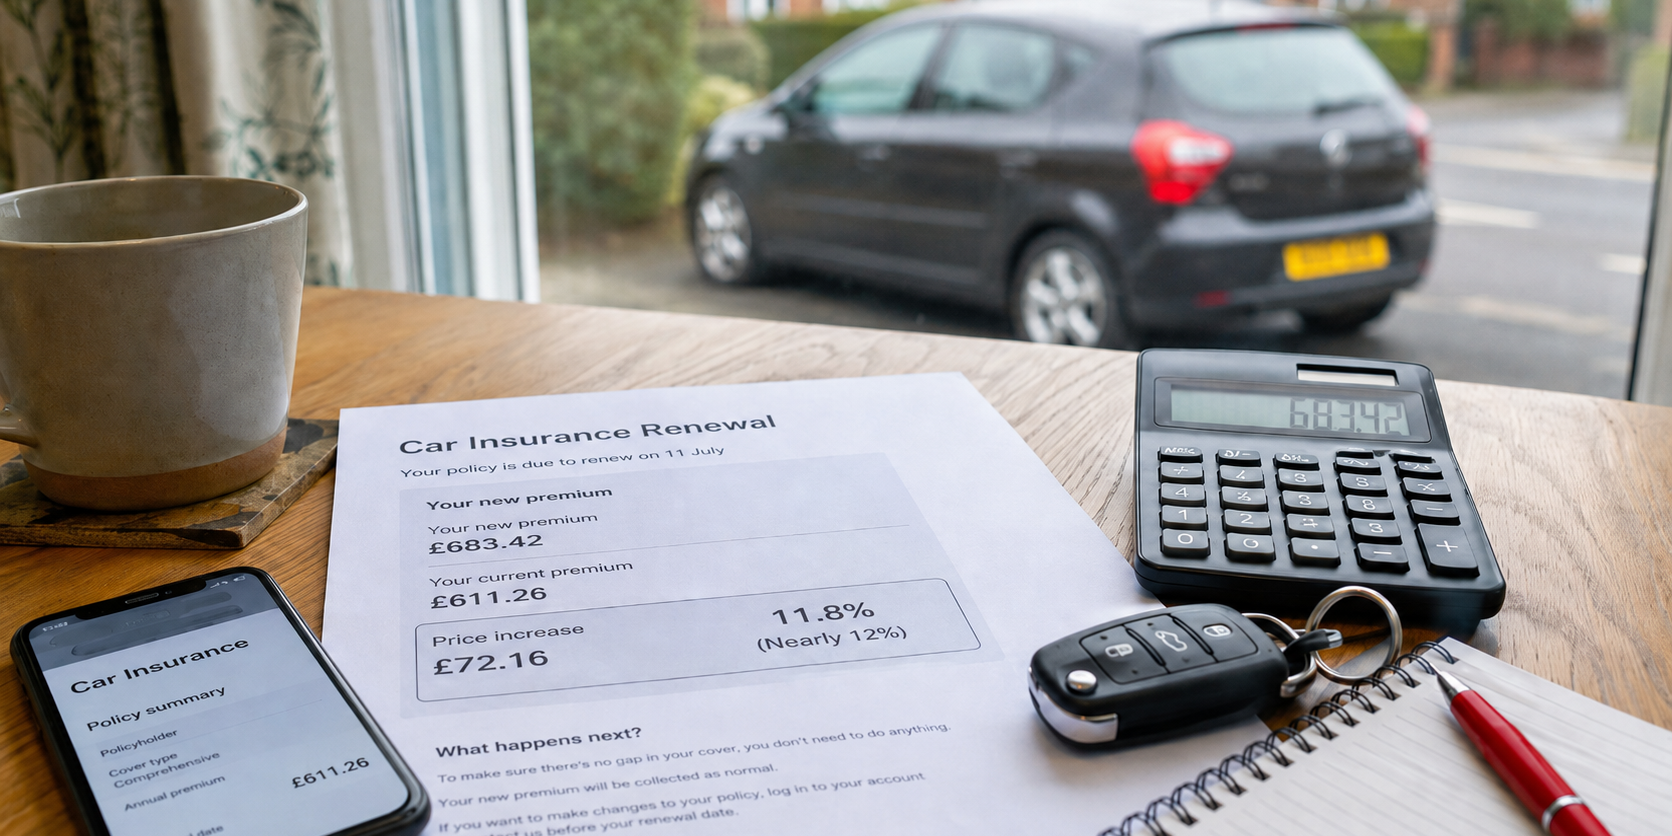
- Full-coverage car insurance will average $2,242 a year by the end of 2026, Insurify projects, with rates still climbing in 32 states.
- Connecticut and West Virginia face the steepest projected increases, up roughly 4 percent and 3 percent respectively in the second half of the year.
- Drivers in Washington, D.C. already pay the most in the country at $3,880 a year, while seven states plus D.C. now average more than $3,000.
Your Renewal Notice Is About to Get More Expensive
Car insurance bills are rising again, and the increase is not limited to a handful of high-cost states. Insurify’s Mid-Year Auto Insurance Report, built from 250 million rates in its database, projects that 32 states will see full-coverage premiums climb further before the year ends, on top of increases that 27 states already recorded in the first half of 2026.
The national average for full-coverage car insurance sits at $2,237 a year right now, up 1 percent since the end of 2025. Insurify expects that average to reach $2,242 by December, a modest national number that hides sharp regional differences. Drivers in the most expensive states are paying nearly double the national figure, and the gap between the cheapest and most expensive states keeps widening.
Where Rates Are Rising Fastest
Connecticut leads the country in projected increases for the rest of 2026, with Insurify forecasting premiums up nearly 4 percent by year end. West Virginia follows closely at roughly 3 percent. Both states have seen repair costs and claims severity rise faster than their state insurance regulators have historically approved rate changes, and insurers in both states have been filing for larger rate hikes to catch up.
Washington, D.C. remains the most expensive place in the country to insure a car, with drivers there paying $3,880 a year on average for full coverage. Seven states join the District above the $3,000 mark. Not every expensive market is rising, though. New York, New Jersey and Washington, D.C. have each seen rates fall slightly so far in 2026 even as they remain among the costliest places to drive, a reminder that a high starting price and a rising price are two different problems.
What Is Driving the Increase
Insurify points to several factors compounding at once. Inflation hit a three-year high in May, pushing up the cost of nearly everything insurers pay out for, from medical treatment after a crash to replacement parts. Gas prices climbed from roughly $3 a gallon to around $4 over the past year in many markets, a cost that does not directly set insurance rates but correlates with how much driving happens and how severe crashes tend to be at higher speeds on more congested roads.
Auto maintenance and repair costs have risen 45 percent over the past five years, driven by more expensive parts, a shortage of qualified technicians and the growing complexity of modern vehicles packed with sensors and cameras that cost far more to replace than a traditional bumper or headlight. Every one of those repair bills eventually works its way into the claims data insurers use to set next year’s rates, which is why premiums tend to lag the actual cost increases by a year or more.
What To Do Before Your Policy Renews
Shop your policy before it renews rather than letting it roll over automatically. Rate increases vary enormously by insurer even within the same state, and drivers who have not compared quotes in a year or more are often the ones absorbing the largest increases because they never see what a competitor would charge for the same coverage.
Ask your insurer directly about every discount it offers. Many carriers have expanded telematics programs that track driving habits through a phone app or a plug-in device and offer meaningful discounts, sometimes 10 percent or more, to drivers who avoid hard braking and late-night trips. Bundling home or renters insurance with an auto policy, maintaining a clean driving record and raising your deductible are all still reliable ways to bring a quote down, though a higher deductible only makes sense if you have the savings to cover it after a claim.
Review your coverage limits rather than just your premium. Some drivers respond to a rate increase by dropping comprehensive or collision coverage on an older vehicle, which can make sense if the car’s value has fallen below a few thousand dollars, but is a costly mistake on a newer vehicle still worth repairing after an accident.
What Happens Next
Insurify’s forecast runs only through the end of 2026, and nothing in the current data suggests the pressures behind this year’s increases are easing. Repair costs, inflation and claims severity all move slowly, and insurers typically need a full year of updated data before filing for a rate change with state regulators. Drivers in Connecticut and West Virginia should expect the steepest increases to show up on renewal notices arriving between now and early 2027, while drivers in states where rates have already started falling, including New York and New Jersey, may see that relief continue if claims trends hold.
Sources:

Leave a Comment
More in News

Why Brake Fluid Needs Changing Every Two Years (and What It Costs)
Why Your Car Pulls to One Side (and What a Wheel Alignment Costs)
How to Tell if a Slow Puncture Is Repairable (and What It Costs)

How to Check and Top Up Your Car Coolant Without Damaging the Engine
What a New DVLA Eyesight Test Could Mean for 6 Million Older Drivers
Trending on Motoring Chronicle
What New CPR and Defibrillator Questions Mean for Every Learner Driver in 2026
Return of an icon: Land Rover Classic launches Classic Defender V8 Soft Top [Photo Gallery]

How the £3,750 Electric Car Grant Works (and Which Models Now Qualify)

London’s Congestion Charge Now Costs Commuting Drivers £4,500 a Year, TfL Data Shows
