
How to Check If You Are Owed a Share of the £7.5 Billion Car Finance Payout


Millions of people who bought a car on finance over the past two decades are now a step closer to getting money back. The Financial Conduct Authority has confirmed an industry wide compensation scheme that is expected to return around £7.5 billion to drivers, with the average payout estimated at roughly £830 for each affected agreement. From 31 May the regulator lifts the pause that has held up motor finance complaints, which means lenders can start working through the backlog and telling customers whether they are owed anything.
If you bought a car, van or motorbike using hire purchase or a personal contract purchase deal between April 2007 and November 2024, there is a reasonable chance you are caught up in this. Here is what the scheme covers, who is likely to receive a payment, and the steps to take so that you keep every penny you are owed rather than handing a third of it to a claims firm.
What the regulator has actually decided
The dispute centres on something called a discretionary commission arrangement. For years, lenders allowed car dealers and brokers to set the interest rate on a finance deal, then paid them a bigger commission the higher that rate was. The driver was rarely told this was happening. The arrangement gave the person selling the car a direct financial reason to push up the cost of borrowing, and the FCA banned the practice in 2021.
After a Supreme Court case and months of consultation, the FCA finalised its redress scheme in its policy statement earlier this year. Rather than forcing every customer to fight their own corner, the regulator has built a single structured process that lenders must follow. The headline figure is around £7.5 billion across the market. The FCA estimates that about 12.1 million finance agreements taken out between 6 April 2007 and 1 November 2024 could fall within scope, and that if roughly three quarters of eligible customers come forward the average redress will land at about £830 per agreement.
Who qualifies and how much you could get
The scheme is aimed at people whose deals involved a discretionary commission arrangement or other unfair commission practices. Because the rules applied across most of the motor finance market during those years, a very large number of ordinary buyers are likely to be included. If you took out PCP or hire purchase to fund a vehicle in that window, you are a candidate, whether the car was new or used and whether you bought from a franchised dealer or an independent forecourt.
The figure of £830 is an average rather than a fixed sum. What you actually receive depends on how much you borrowed, the interest rate you were charged, how long the agreement ran and how much extra you paid as a result of the inflated commission. Someone who financed a £30,000 family car over four years at a marked up rate could be owed considerably more than the average, while a smaller, shorter deal might return less. Multiple agreements mean multiple potential payments, so a household that has financed two or three cars since 2007 should check each one separately.
It is worth being realistic. Not every agreement from this period involved a discretionary commission, and some lenders structured their deals differently. The point of the scheme is that you no longer have to prove the technical detail yourself. The lender has to check its own records and tell you where you stand.
How to claim without paying a penny to anyone
The most important thing to understand is that you do not need a claims management company or a solicitor to take part. The FCA has been blunt on this point, warning that anyone who signs up with a claims firm could lose more than 30 per cent of any money they receive in fees. The scheme is designed to be free and to work directly between you and your lender.
There are two routes. If you have already complained, or you complain before the end of the relevant implementation period, your lender has three months from the end of that period to tell you whether you are owed compensation and how much. People in this group are likely to be dealt with sooner. If you have not complained, lenders are required to contact you only if their records suggest you are likely to be owed money, and they have six months to do that. Anyone who is not contacted but believes they have a case has until 31 August 2027 to make a claim.
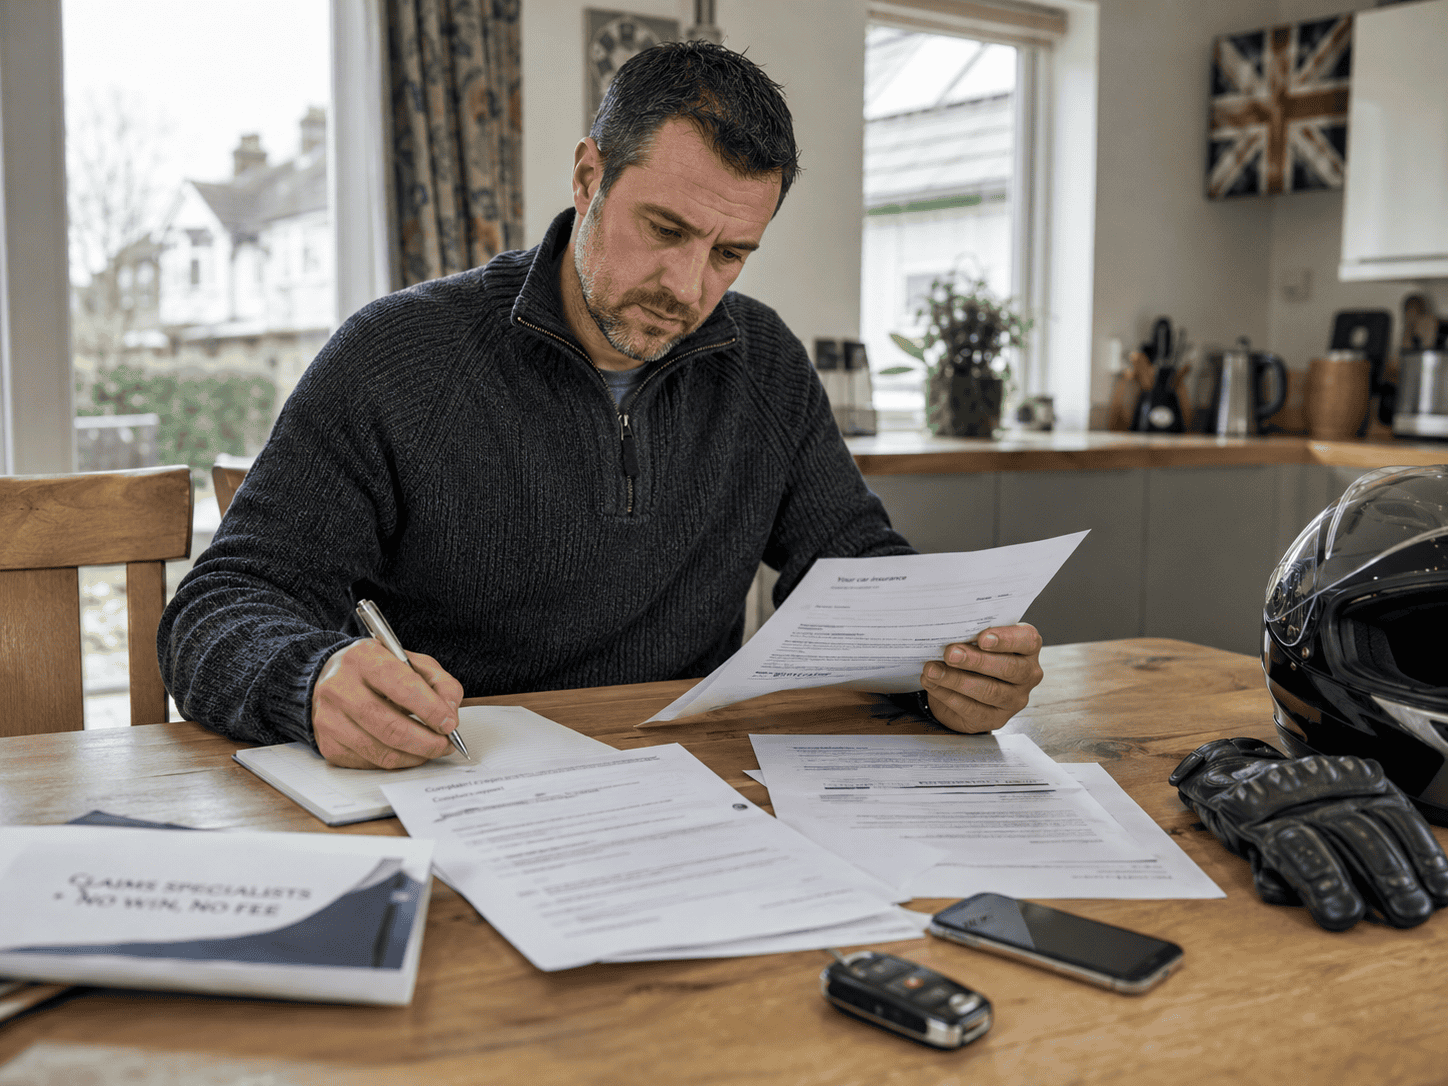
The practical steps are simple. Dig out any paperwork for cars you financed since 2007, including the finance agreement number and the name of the lender, which is not always the same as the dealer. If you no longer have the documents, your lender should still be able to trace the agreement from your name, address and date of birth. Make a short written complaint to the lender stating that you believe your agreement involved a discretionary commission arrangement and that you want it reviewed under the FCA redress scheme. Keep a copy and note the date. If the lender rejects your complaint and you disagree, you can escalate it to the Financial Ombudsman Service free of charge.
Be alert to the rush of adverts and cold calls that schemes like this always attract. A genuine lender or the Ombudsman will never ask you to pay an upfront fee to release your money, and any message that creates artificial pressure to sign a contract quickly should be treated with suspicion.
What happens next and the dates to watch
From 31 May the pause on handling motor finance complaints is lifted, so lenders can begin processing cases in earnest. The FCA expects millions of claims to be settled during the rest of this year, with the large majority resolved by the end of 2027. Payments will be made directly into customers’ bank accounts once a claim is agreed.
For drivers, the sensible approach is to act early, keep records and avoid paying anyone for a service you can carry out yourself in a few minutes. A refund of several hundred pounds, or more, is a meaningful sum at a time when the cost of keeping a car on the road keeps climbing. With used car values falling and many owners already in negative equity, and with running costs under pressure from every direction, money that is genuinely owed to you is worth reclaiming.
What to do
Check whether you financed any vehicle between April 2007 and November 2024. Find the lender’s name and the agreement number for each deal. Make a free written complaint to the lender asking for a review under the FCA scheme, and keep a copy. Wait for the lender’s response within the regulator’s timetable, and escalate to the Financial Ombudsman if you are unhappy. Do not use a paid claims firm, and make a note of the 31 August 2027 deadline if you have not been contacted.
The sheer scale of this is hard to overstate. At £7.5 billion it is one of the largest consumer redress exercises the country has seen since the payment protection insurance scandal, which ultimately returned around £38 billion to the public. Motor finance grew rapidly over the same period, with the great majority of new and used cars bought on some form of credit, so the pool of potentially affected agreements is enormous. That is precisely why the regulator chose a single, structured scheme rather than leaving 12 million people to argue their cases one by one through the courts, a process that would have taken years and enriched the legal industry rather than ordinary drivers.
Sources:

Leave a Comment
More in News

Buyers of Cars Over 10 Years Old Now Pay £751 More, Cazoo Data Shows
Belfast Drivers Pay £892 for Car Insurance, £309 More Than Causeway Coast, Quotezone Shows

DfT Could Cut the 2030 Electric Car Target From 80 to 50 Percent

Every UK Driver Risks a £590 Repair Bill as Pothole Reports Triple, RAC Says

How a 1965 Ford Transit Van Became Worth £17,200, More Than Many New Cars
Trending on Motoring Chronicle

Government Orders a Review Into Public EV Charging Costs After a 38 Percent Price Rise
Honda Recalls 325,588 Odyssey Minivans Over Rearview Cameras That Fail in the Rain

A master of air: crafting a new generation of roadster design with the Bugatti W16 Mistral [Photo Gallery]

Kia EV4 Becomes First Kia to Qualify for Full £3,750 Electric Car Grant
