Modern Car Write-Offs Are Leaving Drivers £2,500 Out of Pocket After a Crash
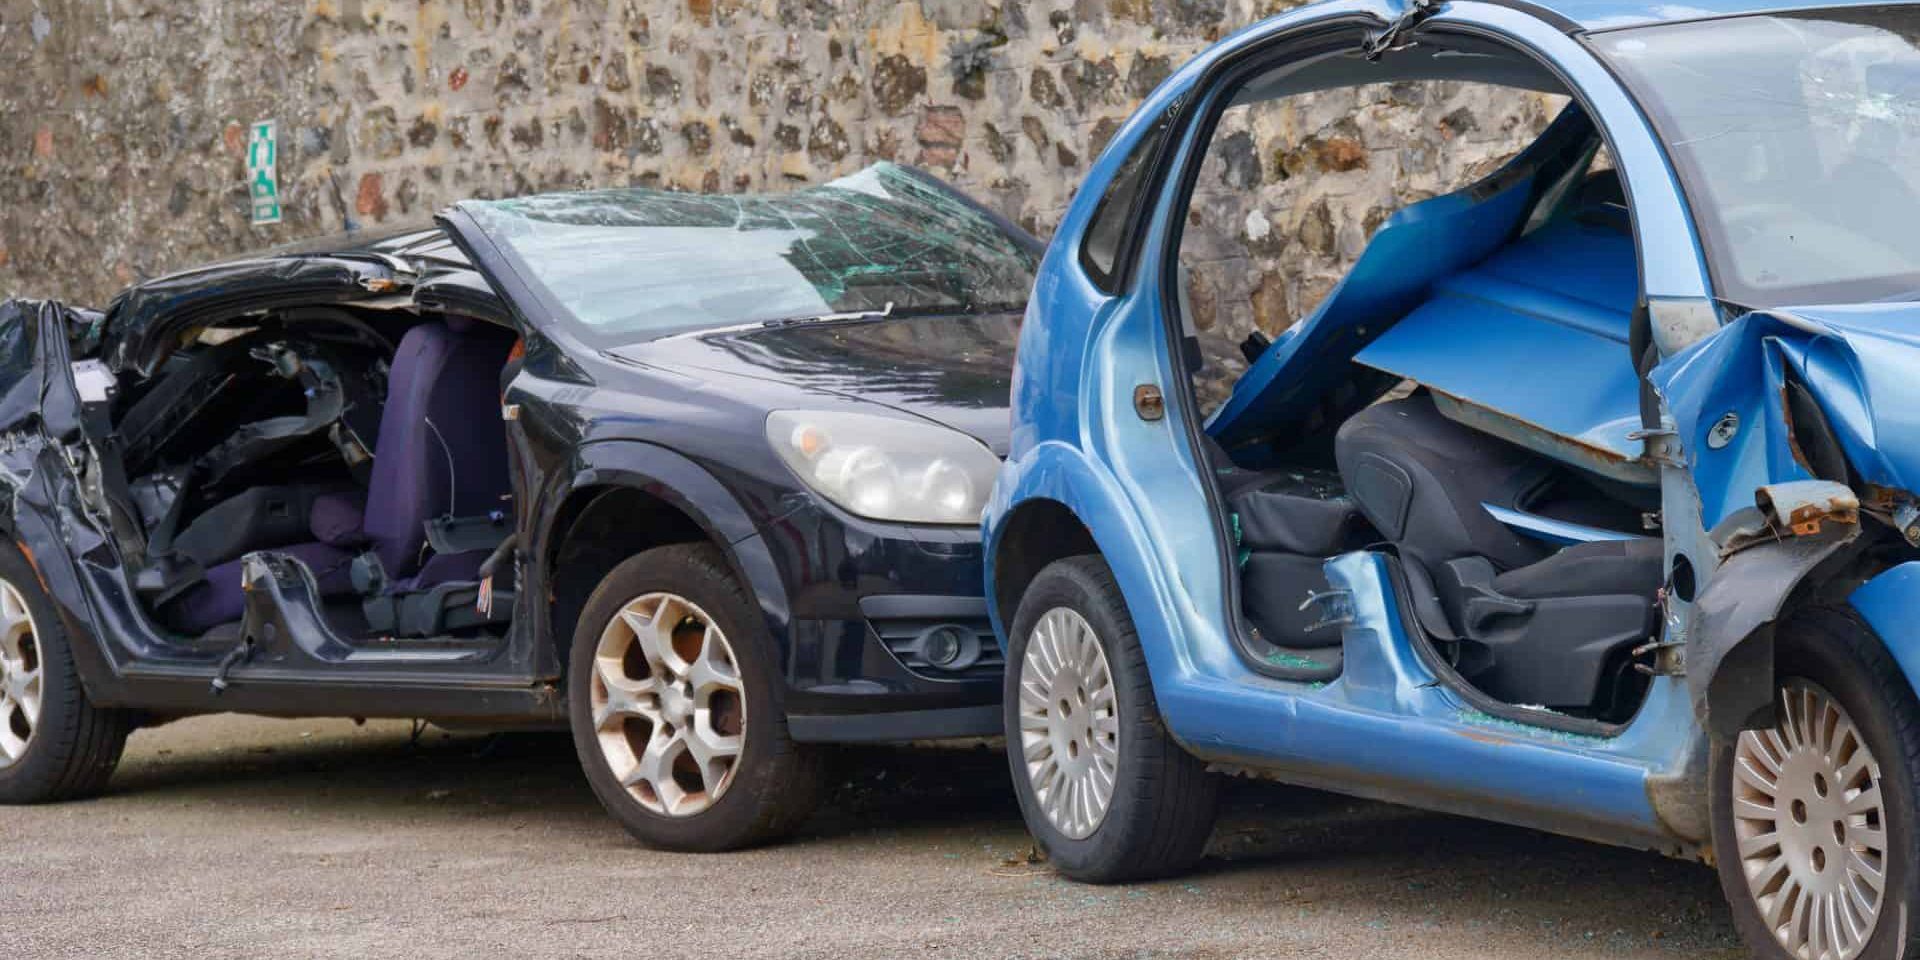
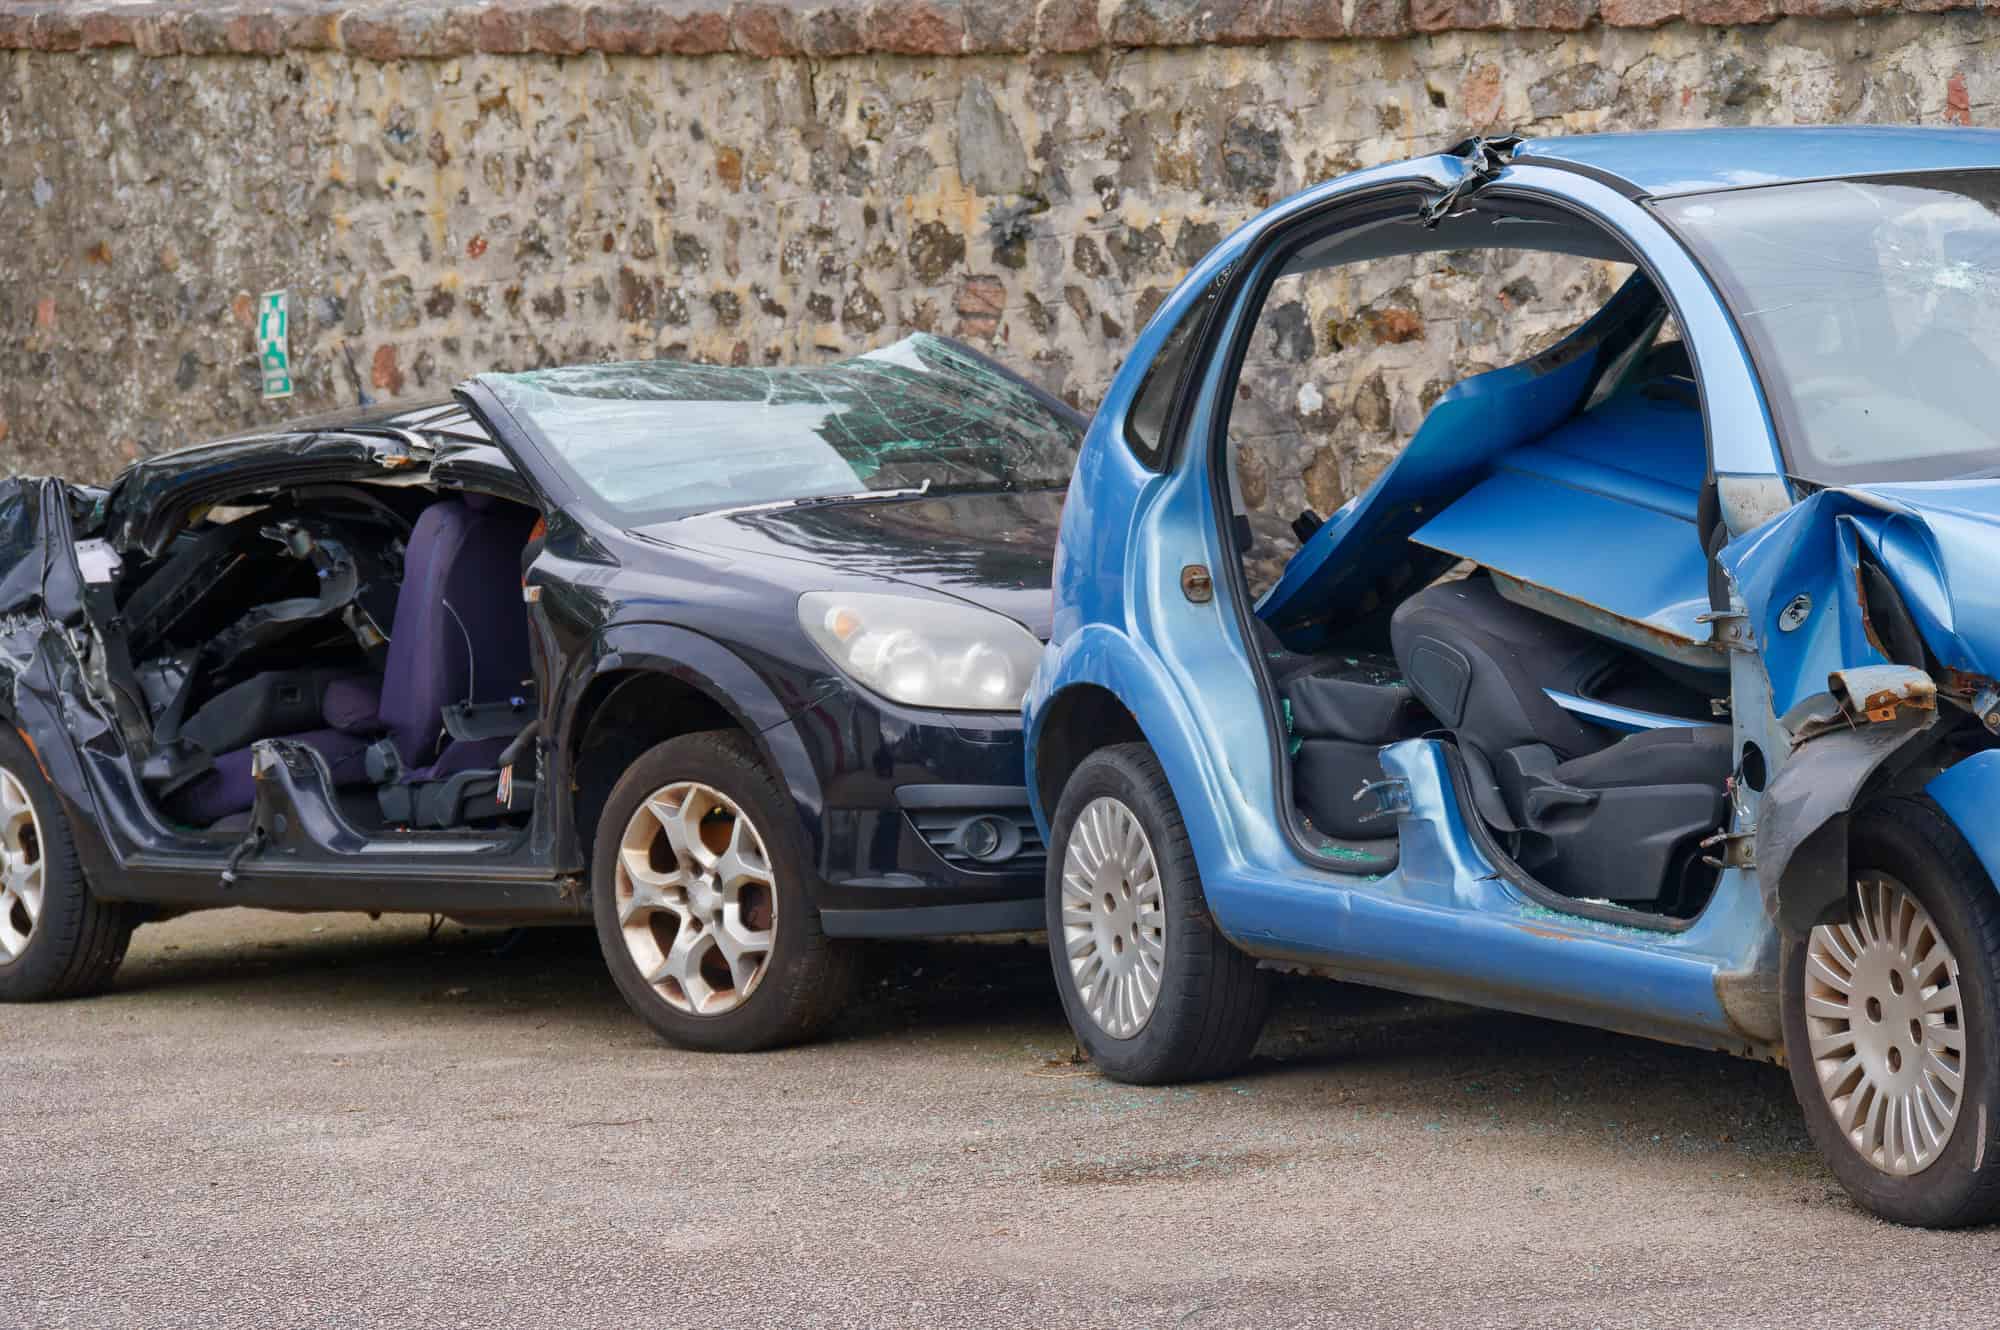
A low speed shunt that once meant a few days at the body shop now increasingly means the end of the car. A growing share of crashes are being declared total losses, and when that happens the cheque from the insurer often falls well short of what it costs to buy the same car again. Industry analysis suggests the gap between a typical total loss payout and the real world price of a like for like replacement has climbed past £2,500, leaving drivers who did nothing wrong out of pocket through no fault of their own.
This is one of the least understood risks in modern motoring, because it has nothing to do with how carefully you drive and everything to do with how cars are now built and valued. Here is why write offs are rising, why the payout so often disappoints, and what you can do to protect yourself before a crash, not after.
Why So Many Cars Are Now Written Off
A car is declared a total loss, or write off, when the cost of repairing it is judged too high relative to its value. That calculation has shifted sharply against repair in recent years. Modern cars are built from a mix of high strength steel, aluminium and composite materials chosen to crumple in a controlled way and protect the people inside. They do that job well, but unlike the mild steel of older cars they cannot simply be heated and beaten back into shape. Damaged sections often have to be replaced as complete assemblies.
On top of that, bumpers and panels are now packed with sensors, cameras and radar units for parking aids, automatic braking and lane keeping systems. A modest knock that cracks a bumper can also destroy several hundred pounds of electronics and require specialist recalibration afterwards. Add rising labour rates and the cost of parts, and the repair bill on what looks like minor damage can quickly climb past the point where an insurer decides the car is not worth saving. The result is that more than a quarter of road traffic incidents are now ending with a vehicle being declared a total loss, according to industry estimates.
Why the Payout Falls Short
When a car is written off, a comprehensive policy pays its market value, meaning what the car was worth the moment before the crash, not what you paid for it and not what it costs to replace today. In a market where used car prices have been volatile, that figure can feel low, and drivers are often surprised by how little their insurer values the car at.
The squeeze is worst for anyone who bought on finance. If you are still paying off a Personal Contract Purchase or hire purchase agreement, the settlement figure you owe the lender can be higher than the market value the insurer pays out. That leaves you needing to clear the shortfall out of your own pocket before you can even think about replacing the car. It is the same trap we described when we reported that millions of drivers owe more than their car is worth as used values tumble, and a write off turns that paper problem into a real one overnight.
The wider cost of all this lands on every policyholder. The Association of British Insurers reported that the average comprehensive motor premium was around £560 in the first quarter of 2026, with insurers paying out £2.9 billion in claims in a single quarter, of which £1.9 billion went on repairs. As repair and replacement costs rise, those payouts feed straight back into the premiums everyone pays at renewal.
The Gap Insurance Question
This is where Guaranteed Asset Protection, usually called gap insurance, comes in. A gap policy is designed to cover the difference between the market value your insurer pays and either the price you originally paid or the amount you still owe on finance. For a driver who has just lost a nearly new car in a crash, that difference can run to thousands of pounds, which is why the product exists.
Gap insurance is not right for everyone, and it is not free, so it pays to understand it rather than buy it on the spot. Dealers often sell it at a premium when you collect a new car, yet standalone policies bought separately are frequently far cheaper for the same cover. The product is most valuable to people who buy new or nearly new, who keep cars on finance, or who would struggle to absorb a several thousand pound shortfall. A driver in an older car worth a modest sum has far less to protect and may not need it at all. As with any insurance decision, weigh the cost against the size of the loss you are actually exposed to, and remember that this is general information rather than personalised financial advice.
How To Protect Yourself
Start by knowing your numbers. Check what your car would realistically sell for today, and if it is on finance, ask your lender for the current settlement figure. If the settlement is higher than the market value, you have a shortfall you would have to cover after a write off, and that is the gap a policy would close.
If you decide gap cover makes sense, compare standalone providers rather than signing whatever the dealer offers, and read the limits carefully, including any cap on the payout and the maximum age or value of car covered. If you already have a policy, check whether it pays to the invoice price or only to the finance balance, because the two can differ significantly.
Beyond gap insurance, the basics still count. Make sure your main policy is set to a fair market value and challenge a low total loss offer if you have evidence of higher prices for the same model, age and mileage. Keep service records and photographs, which help you argue for a stronger valuation. And resist the temptation to cut your cover to save money, a false economy we warned about when we reported that one in eight drivers has cut their cover and risks a £4,900 bill. Younger motorists, who often carry the highest premiums, have at least seen some relief lately, as we explained in our look at why young drivers are paying the lowest car insurance in a decade.
The uncomfortable truth is that the rising tide of write offs is baked into the way modern cars are designed and priced, and it is not going to reverse. A driver cannot change that, but they can make sure that if the worst happens, the insurance cheque actually puts them back behind the wheel rather than leaving them thousands of pounds adrift. Checking your valuation, understanding your finance position and deciding on gap cover with open eyes is the difference between an inconvenience and a financial setback.
Sources:
- https://www.abi.org.uk/products-and-issues/choosing-the-right-insurance/motor-insurance/written-off-or-total-loss-vehicles/
- https://www.moneysavingexpert.com/insurance/car-insurance/what-happens-if-my-car-is-written-off/
- https://www.abi.org.uk/products-and-issues/topics-and-issues/motor-premium-tracker/

Leave a Comment
More in News
NHTSA Offers $1.5 Million for States to Flag Open Recalls at Registration
EV Drivers Pay 82p a kWh at Rapid Chargers, Up 8 Percent, Zapmap Shows
Kia EV2 Named 2027 Car of the Year With £3,750 Grant on Long Range Models
What a £1,000 Fine Means for Drivers Who Flash Headlights to Warn of Cameras
How the AA Wants to Replace the Second £62 Test for Automatic Licence Holders
Trending on Motoring Chronicle

Windscreen Repairs Now Cost £283 on Average as ABI Reports Record £3.2bn Motor Payouts
Northern Ireland Drivers’ Car Insurance Jumped £73 in Three Months, WTW Shows
Ford Recalls 11,405 Rangers After Fake Parts Knock Out the Backup Camera
East Suffolk Council Used £1.1 Million of Car Park Fees to Cover Street Enforcement