How to Tell if a Car Was Written Off Before You Buy It

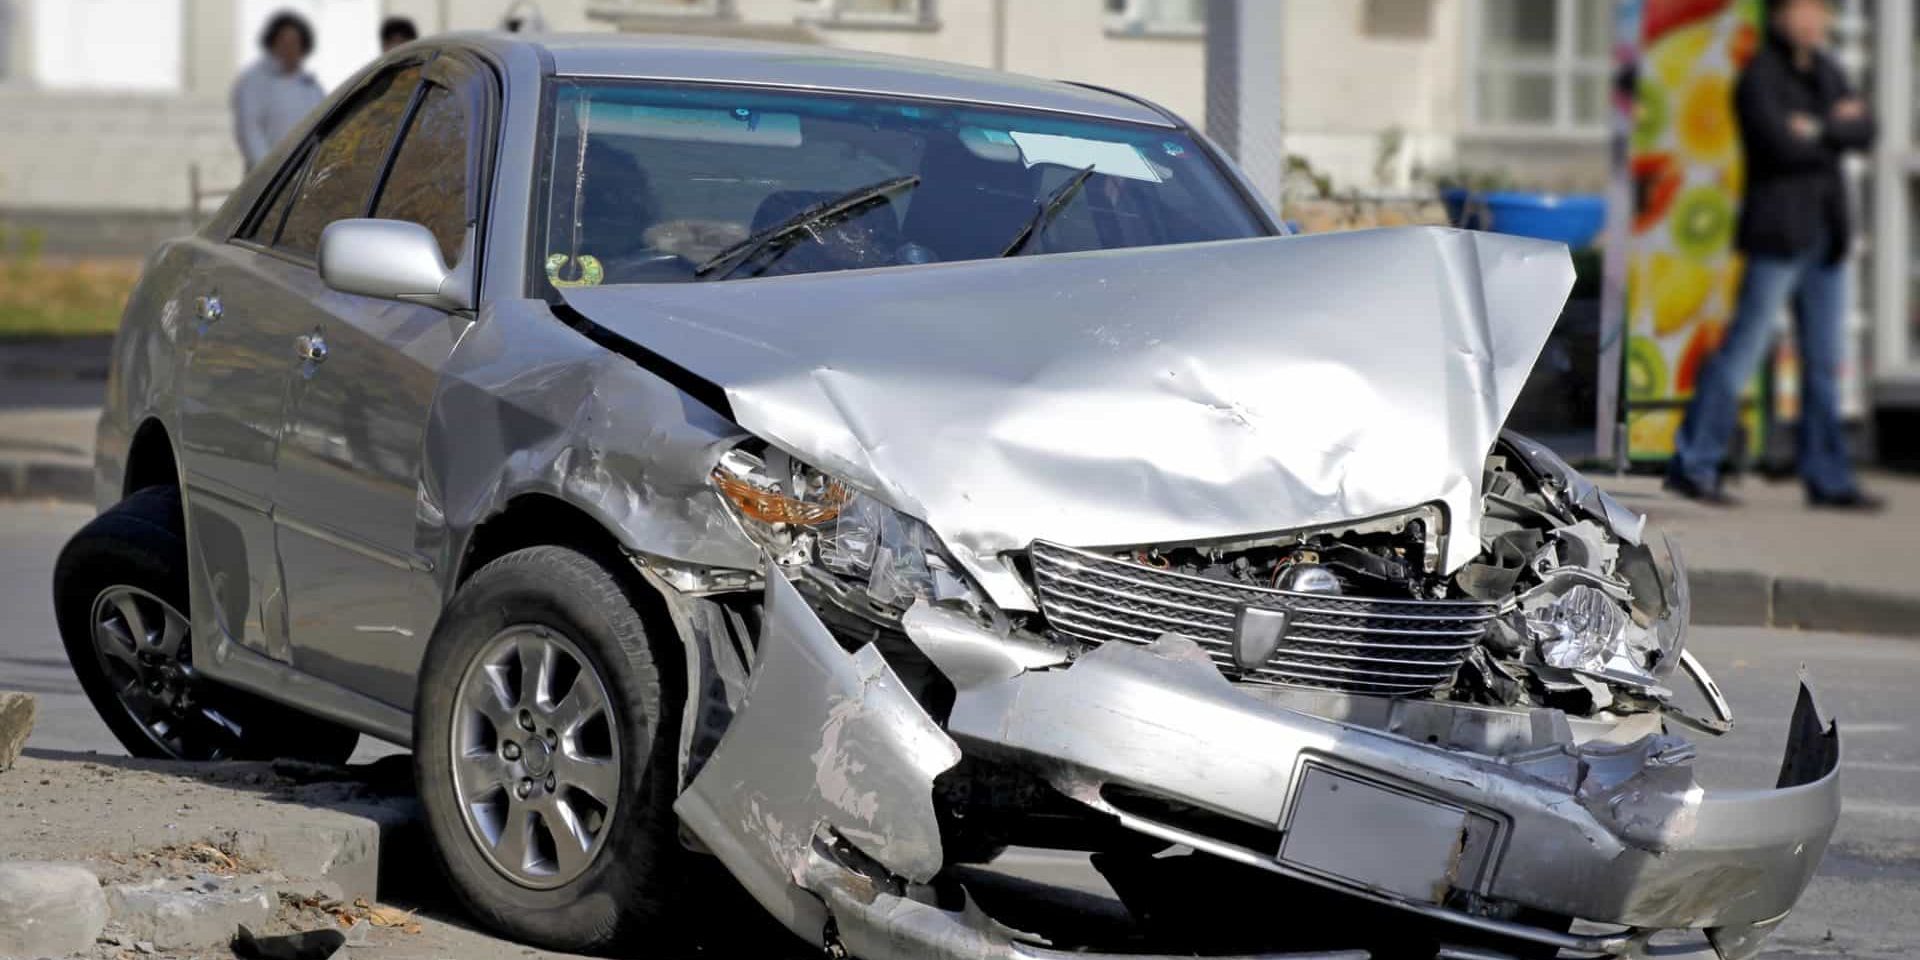
- A car can be legally back on the road after a serious crash, and a private seller has no legal duty to mention it unless you check the V5C logbook and run a history search yourself.
- The four write-off categories, A, B, S and N, describe entirely different levels of risk. Cat A and Cat B cars should never return to the road at all, while Cat S and Cat N can be driven safely once properly repaired.
- A history check costing as little as £9.99 (about $13) can reveal a write-off marker that could otherwise cost you thousands in repairs, a higher insurance premium, or a car no insurer will touch.
The Four Write-Off Categories Every Used Car Buyer Should Check
The Straight Answer: Check the V5C, Then Run a History Search
Before you hand over a deposit on any used car, look at the V5C registration certificate for a note in the “vehicle status” section, then pay for an independent history check from a provider such as HPI, the AA, or a comparable service. A write-off marker gets logged against the vehicle’s registration with the DVLA once an insurer declares the car a total loss, and that record follows the car for as long as it exists, regardless of how many times it changes hands afterwards. A seller who truly does not know the car’s history is common enough: Cat N and Cat S vehicles are frequently repaired and resold by a specialist rather than the original owner, so the check protects you even when nobody is trying to hide anything.
What Cat A, B, S and N Actually Mean
UK insurers classify write-offs under the Association of British Insurers’ Code of Practice for the categorisation of vehicle salvage, updated to version 12 in May 2025 to focus more heavily on structural safety rather than repair cost alone.
Category A is the most severe. The entire vehicle must be crushed, and no parts, not even mechanical components, can be salvaged or resold. Category B allows the mechanical and electrical parts to be reused, but the body shell itself must be destroyed. Neither Cat A nor Cat B cars should legally exist as a driveable vehicle again; if you ever see one advertised for road use, treat that as a serious red flag rather than a bargain.
Category S covers structural damage, meaning the chassis, crumple zones, or roof pillars, the parts designed to protect occupants in a crash, were affected. A Cat S car can return to the road, but only after professional structural repair and DVLA re-registration confirming the work has been checked. Category N covers non-structural damage: the load-bearing structure was untouched, but repair costs still exceeded the car’s pre-accident value, often from extensive cosmetic damage, electrical faults, or airbag deployment. Cat N cars are generally lower risk than Cat S, but non-structural does not automatically mean cosmetic only. Damage to steering geometry, suspension alignment, or braking systems can all fall under Cat N and still affect how safely the car drives.
Why “Cat C” and “Cat D” Still Confuse Buyers
If you are looking at an older used car or an ad written by someone unfamiliar with the current system, the terms Cat C and Cat D can still turn up. The UK replaced this pairing with Cat S and Cat N in October 2017. The old system asked a purely financial question: did the repair cost exceed a set percentage of the car’s value. The current system asks a safety question instead: was the vehicle’s structure damaged. A car marked Cat C under the old rules is roughly equivalent to today’s Cat N, and Cat D maps loosely onto Cat N as well, though the two systems are not a precise one-to-one match. Either way, a Cat C or Cat D marking on an older vehicle’s history should lead to exactly the same checks as a modern Cat S or Cat N record.
The Real Cost and Insurance Risk of Buying a Write-Off
A basic HPI check costs £9.99 (about $13), with a fuller report including a £30,000 guarantee running to £19.99 (roughly $25). The AA charges £14.99 (about $19) for a single check, and cheaper alternatives exist from around £2.95 to £5 (roughly $4 to $6) per vehicle if you are comparing several cars at once. Set against a car that could cost anywhere from a few thousand pounds upward, that is a small outlay to avoid a very expensive mistake.
The financial risk sits mostly on the insurance side. Insurers treat a Cat N marking as a higher-risk vehicle than an equivalent car with no write-off history, which typically means a noticeably higher premium even when the repair itself was completed to a good standard. Cat S cars carry a heavier burden still: several insurers restrict cover or decline it outright without an independent engineer’s inspection report confirming the structural repair meets manufacturer standards, and some lenders will not offer finance against a Cat S vehicle at all. Buying first and discovering the insurance problem afterwards can leave you with a car you are unable to legally drive on your existing policy, and a limited pool of insurers willing to quote at any price.
The Checklist Before You Hand Over Any Money
Start with the V5C and a paid history check every time, even on a car sold by someone you know or trust. The record sits with the vehicle rather than the seller. Ask directly whether the car has ever been declared a write-off, and get the answer in writing if you can, alongside any repair invoices or engineer’s reports the seller holds.
For anything marked Cat S, arrange an independent structural inspection before you commit to buying, not after. A qualified engineer can confirm whether the repair actually restored the car to a safe standard, something a visual check alone cannot tell you. Look over the bodywork for mismatched paint, uneven panel gaps, or overspray inside the wheel arches and door shuts, all common signs of accident repair work that was not declared. Finally, get an individual insurance quote for the specific car before you pay a deposit, not a generic estimate for the model. A quote that comes back far higher than expected, or a flat refusal to cover the car at all, tells you everything you need to know before you are financially committed.
Other Warning Signs a History Check Will Not Catch
A history check confirms whether a write-off marker exists, but it will not describe the quality of a repair or catch damage nobody ever declared to an insurer. The free MOT history checker on GOV.UK is worth running alongside any paid check: look for a mileage figure that drops or jumps unexpectedly between tests, or a cluster of advisories for panel, suspension, or electrical faults appearing all at once, both common signs of an accident that was fixed privately rather than through an insurance claim.
In person, check that all four tyres show even wear alongside one another. A mismatched wear pattern between the front and rear axles can point to a bent subframe or misaligned suspension from a repair that was not done to the original specification. Open the bonnet and boot and compare the VIN plate and chassis stampings against the V5C. Reputable repairers replace these correctly after structural work, but a mismatch, however small, is reason enough to walk away rather than negotiate.
Sources
- Association of British Insurers, Code of Practice for the Categorisation of Motorised Vehicle Salvage, Version 12 (May 2025)
- GOV.UK, “Buying repaired written-off vehicles: a consumer guide”
- RAC Drive, “What is a Cat A, B, S or N insurance write-off?”
- Auto Express, “What are Cat S and N cars? New insurance write-off categories explained”
- HPI and The AA, vehicle history check pricing, 2026

Leave a Comment
More in News

2027 Jeep Wrangler JL-2A Special Edition Adds Retro Style for Just $115 More
What Actually Happens If You Ignore an MOT Advisory

What California’s New Mirrored License Plate Format Means for Your Car
How Long Beach’s New Speed Cameras Will Fine Drivers Up to $500 Starting This Fall

Maryland Drivers Face Up to $1,500 in Fines for Snow-Covered Cars Starting October 1
Trending on Motoring Chronicle
GM EVs Can Power Your Home and Cut Bills Through Bidirectional Charging

How to Stop Condensation Fogging Up Your Car Windows This Autumn

AION UT Launches in UK From £28,950 with 0% Finance Deal

Boosting fuel efficiency, how to improve gas mileage in cars