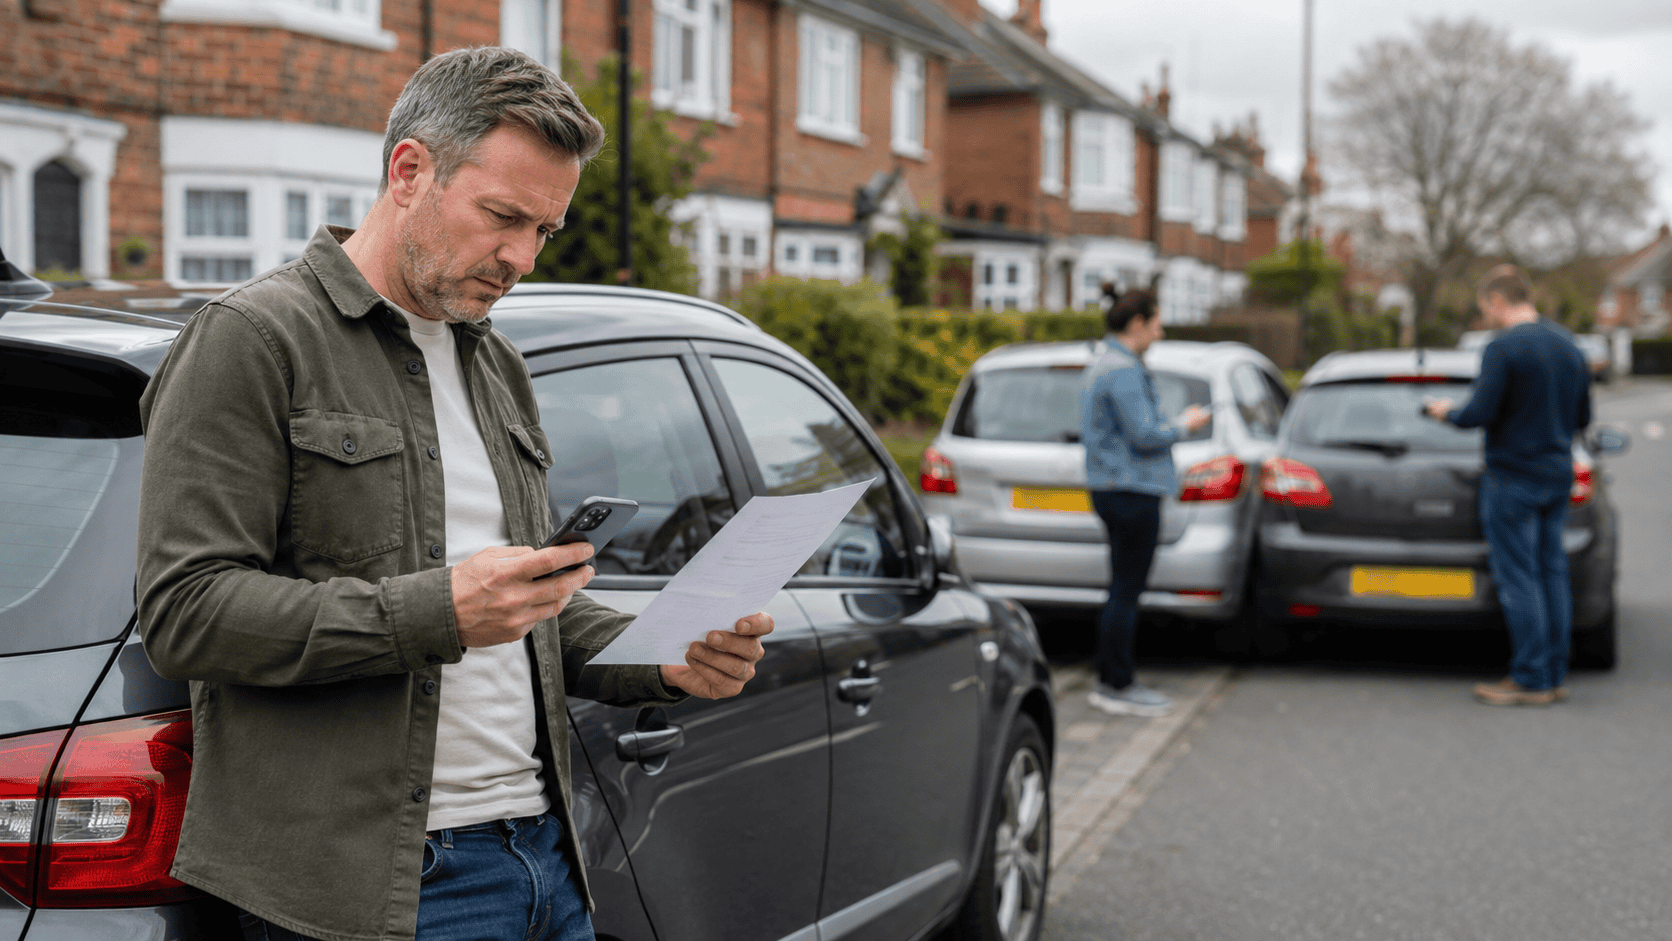
What a 46 Percent Rise in Ombudsman Car Insurance Complaints Means for UK Drivers


- Car and motorcycle insurance complaints to the Financial Ombudsman Service reached 4,100 in the second quarter of 2026, up 46 percent from 2,800 a year earlier.
- Motor finance complaints fell to 5,600 from 24,300 in the same quarter last year, after the Ombudsman said it could not progress many car finance commission cases until legal challenges are resolved.
- The Ombudsman upheld 26 percent of all complaints this quarter, or 30 percent once car finance commission cases are stripped out, and resolved just over half within three months.
The Complaint Numbers Insurers Would Rather You Did Not See
Every driver who has fought an insurer over a write off valuation, a delayed claim payout or a cancelled policy now has company. The Financial Ombudsman Service received 53,600 new cases between April and June 2026, and inside that total, complaints about car and motorcycle insurance climbed to 4,100, a rise of 46 percent on the 2,800 recorded in the same three months of 2025. The increase ran against the overall trend. Total complaints to the Ombudsman fell from 68,000 a year earlier, driven down almost entirely by a collapse in car finance commission cases working through the courts. While that story dominated the headlines, insurance complaints kept climbing underneath it.
James Dipple-Johnstone, the service’s interim chief ombudsman, said the quarter’s figures “highlight the wide range of issues people are bringing to us.” Car insurance sits among the fastest growing of them, and the rise has barely registered next to the commission scandal next door.
Why Finance Complaints Collapsed While Insurance Complaints Climbed
Hire purchase complaints, the category that covers most car finance disputes, dropped from 24,300 in the second quarter of 2025 to 5,600 in the same quarter this year. That is not a sign the car finance commission problem went away. The Ombudsman said directly that it is “not able to progress many” of these cases “until we get clarity on legal challenges” working through the courts. Cases are piling up unresolved rather than being closed, which is why the headline number looks smaller even as the underlying backlog grows.
Insurance complaints carry no such block. An insurer has to give a final response or let eight weeks pass before a complaint can reach the Ombudsman, and from there a decision usually follows within months, not years. That is almost certainly part of why insurance complaints are rising in plain sight while finance complaints vanish into a queue. Drivers unhappy with an insurer are getting a hearing. Drivers unhappy with a finance commission arrangement are, for now, mostly getting a holding pattern.
What Drivers Are Actually Complaining About
Car and motorcycle insurance complaints to the Ombudsman cluster around a handful of recurring disputes. Valuation is the biggest: an insurer writes a car off and offers a settlement figure the owner believes is well below the car’s real market value the day before the crash. Claims delays are the second cluster, where an insurer sits on a simple claim for weeks while a driver pays for a hire car or struggles without one. Service complaints make up a third strand, covering everything from unanswered calls to policies cancelled over paperwork errors the driver never saw. Smaller numbers of complaints cover roadside assistance policies, warranty products sold alongside cover, and disputes over which party was at fault after a collision.
None of these categories require a driver to prove bad faith. The Ombudsman’s test is simpler: did the insurer treat the customer fairly and stick to what the policy actually promised. An uphold rate of 26 percent across all case types this quarter means roughly one in four complainants had their insurer told to pay more, apologise, or put something right. Excluding the stalled finance commission cases, that figure rises to 30 percent, close to one in three.
Why Renewal Season Timing Works Against You
Autumn is when a large share of UK car insurance policies come up for renewal, and it is also when disputes over a previous claim tend to resurface, as an open or contested complaint can affect the premium an insurer quotes at renewal. A driver still arguing over a valuation from the spring, or waiting on a claim that should have been settled months ago, is often quoted a higher renewal premium on the assumption that the claim will eventually be recorded against them. Escalating a stalled complaint to the Ombudsman now, rather than letting it drag into renewal season, can settle the dispute before it has a chance to inflate next year’s premium.
The rise in insurance complaints also lands at an awkward moment for insurers already facing scrutiny over pricing. Regulators have spent recent years pushing the industry to stop charging existing customers more than new ones for the same cover, a practice sometimes called the loyalty penalty. A driver who feels an insurer has quietly treated them worse, whether on price or on a claim, now has a visibly busier Ombudsman watching the same companies, and a visibly higher chance than in previous years of a complaint actually succeeding.
How to Complain and What It Costs You
Taking a dispute to the Ombudsman costs the driver nothing. The process starts with the insurer, not the regulator. A driver has to raise the complaint directly with the insurance company first and either receive a final response letter or wait eight weeks without one. Only then can the case go to the Financial Ombudsman Service, and it has to go within six months of that final response. The complaint can be lodged online or by phone, and no solicitor or claims management company is required.
That last point counts for more than it sounds. Professional representatives, including claims management firms that take a cut of any payout, brought just 10 percent of cases to the Ombudsman this quarter, down sharply from 45 percent a year ago. Drivers are increasingly going direct, and the shift appears to be working in their favour: cases closed within three months of an investigation starting rose to 51 percent, up from 46 percent the year before. A driver who complains directly keeps the whole of any award and tends to get an answer faster than one who pays a firm to do it for them.
What to Do If You Think Your Insurer Got It Wrong
Keep a written record of every call and the name of whoever you spoke to. A verbal promise that never makes it onto the file is the single biggest reason valuation and service complaints stall. If a car has been written off, gather independent evidence of its value before the accident, such as listings for identical models with matching mileage, rather than accepting the insurer’s first number. If a claim has dragged past eight weeks with no final response, that silence itself is grounds to escalate straight to the Ombudsman rather than waiting indefinitely for the insurer to reply. None of this requires paying a claims company a percentage of the outcome. The complaint is free to bring, free to pursue, and increasingly likely, on this quarter’s figures, to end in the driver’s favour.
Two years ago, car finance commission complaints so dominated the Ombudsman’s workload that insurance disputes barely stood out in the published data. That balance has now flipped. With finance cases frozen behind a legal process that has no firm end date, car and motorcycle insurance has become one of the categories actually moving through the system and producing results for the people who bring it. Anyone sitting on an unresolved dispute with their insurer, rather than their finance company, is now in the part of the queue that is working, and the figures suggest that queue is moving faster and paying out more often than it has in years.
Sources:

Leave a Comment
More in News
How California’s New Robotaxi Law Could Fine Waymo and Tesla $10,000

Car Thefts Fell 21 Percent Nationwide, but Los Angeles Remains the Theft Capital

Why Truckers Could Save $100 a Fill Under Trump’s New Diesel Tax Order

Every Driver Pays Up to £4.72 More a Tank by Postcode, AA Finds

Paris Motor Show 2026 highlights, with BYD and Denza leading the charge
Trending on Motoring Chronicle

Kansas Turnpike Tolls Rise Today as Truckers Pay 4% More for a $500 Million Upgrade

GM’s Fuel Pump Recall Has Quietly Spread to Nine of Its Best-Selling Models

Lamborghini Diablo: celebrating 35 years of an icon [Photo Gallery]
Kia wins seven 2026 Best Cars for the Money Awards from U.S. News & World Report