
State Farm Owes Washington Drivers $8.8 Million After a New Settlement

- State Farm will pay $8.8 million to resolve claims that it shortchanged Washington policyholders on underinsured motorist property damage payouts after a crash.
- The money covers diminished value, the drop in a car’s resale price after an accident even when the repair looks perfect, for anyone who filed a UMPD claim in Washington between January 13, 2019, and February 27, 2026.
- A court must still approve the deal at an October 30, 2026, hearing, and the deadline to submit a claim form is December 14, 2026.
The Payout Insurers Rarely Mention on Their Own
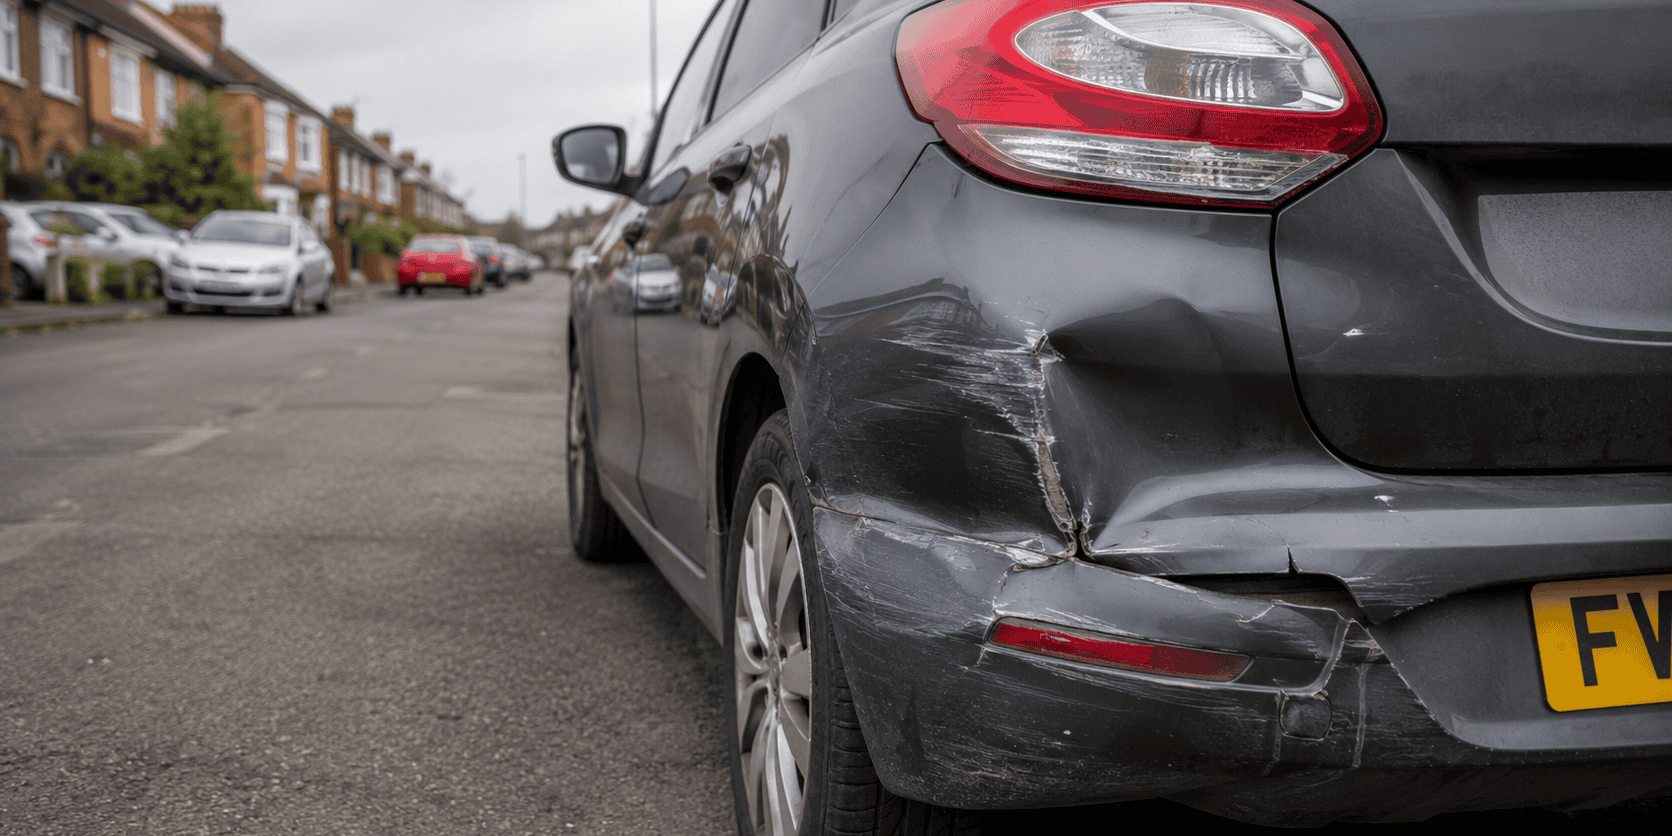
A car that has been in a crash is worth less than an identical car that has not, even after every panel is repaired and every part replaced. Buyers know it, dealers know it, and vehicle history reports like Carfax make sure a car’s accident record follows it for life. Insurance companies know it too, which is exactly why a new $8.8 million settlement in Washington state deserves the attention of anyone who has filed a claim there in the last several years. State Farm is paying out over allegations that it failed to properly compensate drivers for that lost value, known as diminished value, under their underinsured motorist property damage coverage.
The case, Hardy v. State Farm Mutual Automobile Insurance Company, argued that State Farm breached its own policy language by paying only for repairs and ignoring the resale value a car loses simply by having a collision on its record. State Farm has denied any wrongdoing, and the settlement resolves the dispute without an admission of liability. A judge is scheduled to weigh final approval at a hearing on October 30, 2026. If approved, the settlement fund of $8,822,039.83 will be divided among eligible claimants after legal fees and administrative costs are deducted from the total.
Who Qualifies and How Much They Could Get
Eligibility is narrower than a typical class action settlement, which is part of why so few drivers have heard of it. A policyholder qualifies if they held a Washington State Farm auto policy and received a payment under underinsured motorist property damage coverage between January 13, 2019, and February 27, 2026. UMPD coverage is what a driver’s own policy pays out when the other driver at fault does not carry enough property damage liability insurance to cover the repair bill. It is a coverage type many drivers do not realize they are paying for until they need it, and one that fewer than a dozen states require insurers to offer at all.
Individual payouts will vary. The fund is fixed and splits proportionally based on how many valid claims come in and each claimant’s specific vehicle and damage history. Drivers can submit claims online or by mail, with submissions accepted through the settlement website or by calling the case administrator at (833) 930-0261. Anyone who received a UMPD payment from State Farm in Washington across that window should assume they qualify and check rather than skip it on the assumption the amount would be too small to bother with.
Why Diminished Value Claims Are So Easy to Miss
Most drivers only learn what diminished value means when they try to sell or trade in a car that has a collision reported on its title history. The industry’s rough formula, often called the 17c method after the insurance bulletin that popularized it, starts with the vehicle’s pre-accident value, applies a damage severity multiplier, then reduces the total further based on mileage. A $30,000 vehicle with moderate structural damage might see its diminished value calculated in the hundreds of dollars using that formula, though independent appraisers frequently find the real-world resale hit runs larger once a buyer sees “accident reported” on a history report.
State law on who has to pay this varies enormously. Georgia is the rare state that requires an insurer to pay diminished value directly to its own policyholder. In most other states, including Washington, drivers typically pursue diminished value against the at-fault driver’s insurer, or in this case, against their own UMPD coverage standing in for an underinsured driver. That patchwork is a big reason diminished value claims go unfiled: drivers do not know the coverage exists, do not know which party is supposed to pay it, and insurers are under no obligation to volunteer the option on their own.
Part of a Wider Pattern Across the Country
Washington is not an isolated case. State Farm and other major insurers have faced a string of similar disputes in recent months, including a Louisiana settlement over total loss handling fees and a separate Michigan case involving USAA and tax and title fees on total loss claims. Each of these settlements targets a different technical gap in how insurers calculate what they owe after a crash, whether that is diminished value, sales tax on a replacement vehicle, or administrative fees baked into a payout. Taken together, they point to the same underlying problem: total loss and property damage payouts are complicated enough that insurers can systematically shortchange policyholders in ways that only surface once a lawsuit forces the numbers into the open for everyone to see.
Consumer advocates who track these cases argue the pattern should push every driver, not just those in an active lawsuit, to read the settlement details on any total loss or UMPD payout closely, and to ask their adjuster directly whether diminished value was calculated and included in the offer. An insurer has no obligation to bring it up unprompted, and the burden generally falls on the driver to ask the question first.
How This Settlement Compares to Others on the Books
Put next to other recent auto insurance settlements, the Washington deal is modest in dollar terms but broad in reach. A Louisiana settlement over State Farm’s handling of total loss claims and a Michigan settlement covering USAA’s tax and title fee practices both involved different specific mechanics, yet all three cases share a common thread: an insurer’s internal formula for calculating what it owes came up short in a way that only a lawsuit, rather than a routine claim dispute, was able to correct. None of the three companies admitted wrongdoing, and each resolved its case through a negotiated fund rather than a court-ordered payout after trial. For policyholders, the practical lesson is the same across all three states: an insurer’s first offer on a claim is a starting point for negotiation, not a final number handed down from a neutral authority.
Attorneys who represent policyholders in these disputes point out that insurers rarely change their claims-handling formulas voluntarily after a settlement like this one. The $8.8 million fund resolves past claims within the class period, but it does not automatically change how State Farm calculates UMPD payouts in Washington going forward unless the settlement terms specifically require a process change. Drivers filing a UMPD claim today should still ask directly whether diminished value is included in an offer, rather than assuming this settlement fixed the underlying calculation for good.
What Washington Drivers Should Do Now
Anyone who filed a UMPD claim with State Farm in Washington between January 13, 2019, and February 27, 2026, should visit the settlement website and confirm their eligibility ahead of the December 14, 2026, deadline. Claimants should keep a copy of their original claim paperwork and payout documentation on hand, as the administrator can request it to verify eligibility before releasing payment. Drivers should also watch for the outcome of the October 30 court hearing. Final terms could shift slightly if the judge requires changes before granting approval.
More broadly, any driver anywhere in the country who has had a car declared a total loss or repaired after a crash should ask their insurer directly whether diminished value factored into the payout, and should get an independent appraisal if the answer is no. Given how often these calculations end up disputed in court years after the fact, checking at the time of the original claim is far simpler than waiting for a class action to correct it later. A five-minute question to an adjuster today can save months of paperwork and a smaller check tomorrow.
Sources:

Leave a Comment
More in News

Suzuki Cuts e-Vitara Price to £24,999 in Range-Wide Savings
What the UK Tyre Tread Limit Actually Means (and How to Check Yours)
Drivers Aged 19 Now Pay £1,853 for Car Insurance, Confused.com and WTW Show
Kia Will Refund up to $400 for This Power Window Repair before Nov. 23

How New State Laws Are Limiting What Police Can Do with Your License Plate Data
Trending on Motoring Chronicle

A 10mm Windscreen Chip in the Wrong Spot Will Fail Your MOT

What the Engine Management Light Actually Means (and When to Stop Driving)
The £10 Fix Most Drivers Have Never Heard Of That Could Transform Your Car’s Air Quality This Spring

Ford Recalls 565,691 Broncos Over Wiring That Can Spark Engine Fires
