Why the Average Car Repair Bill Just Hit $838
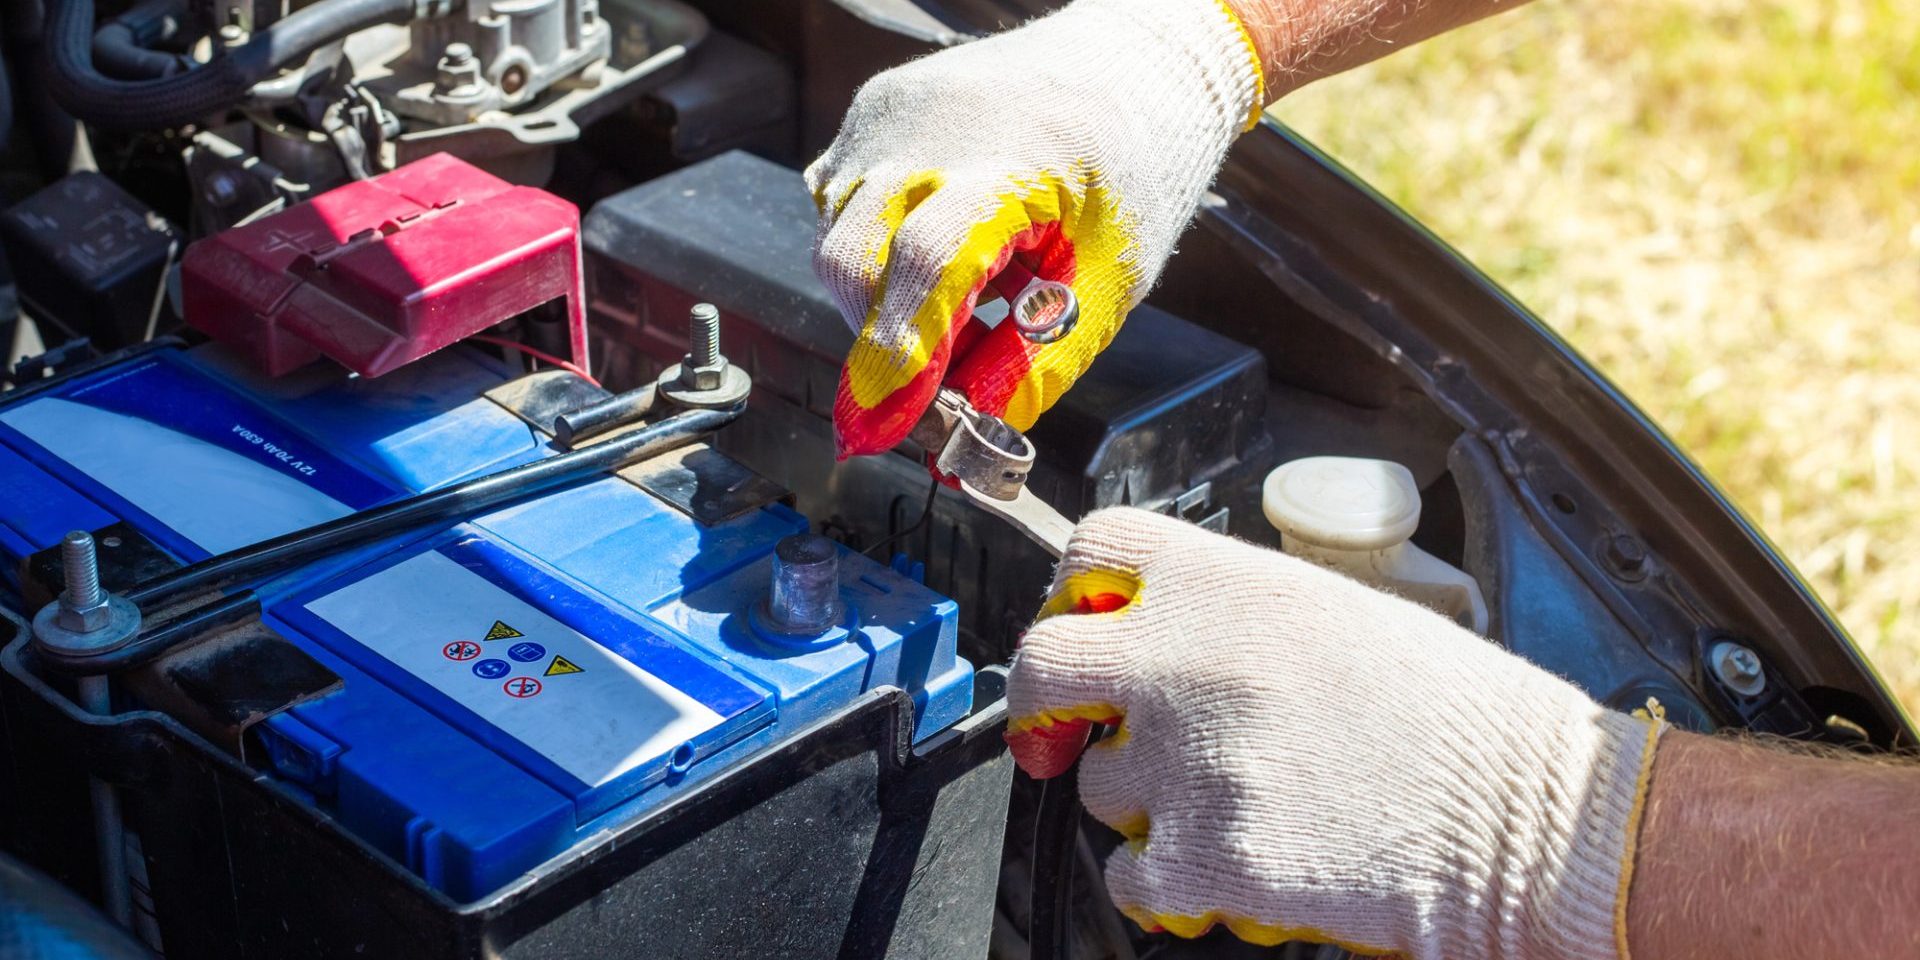
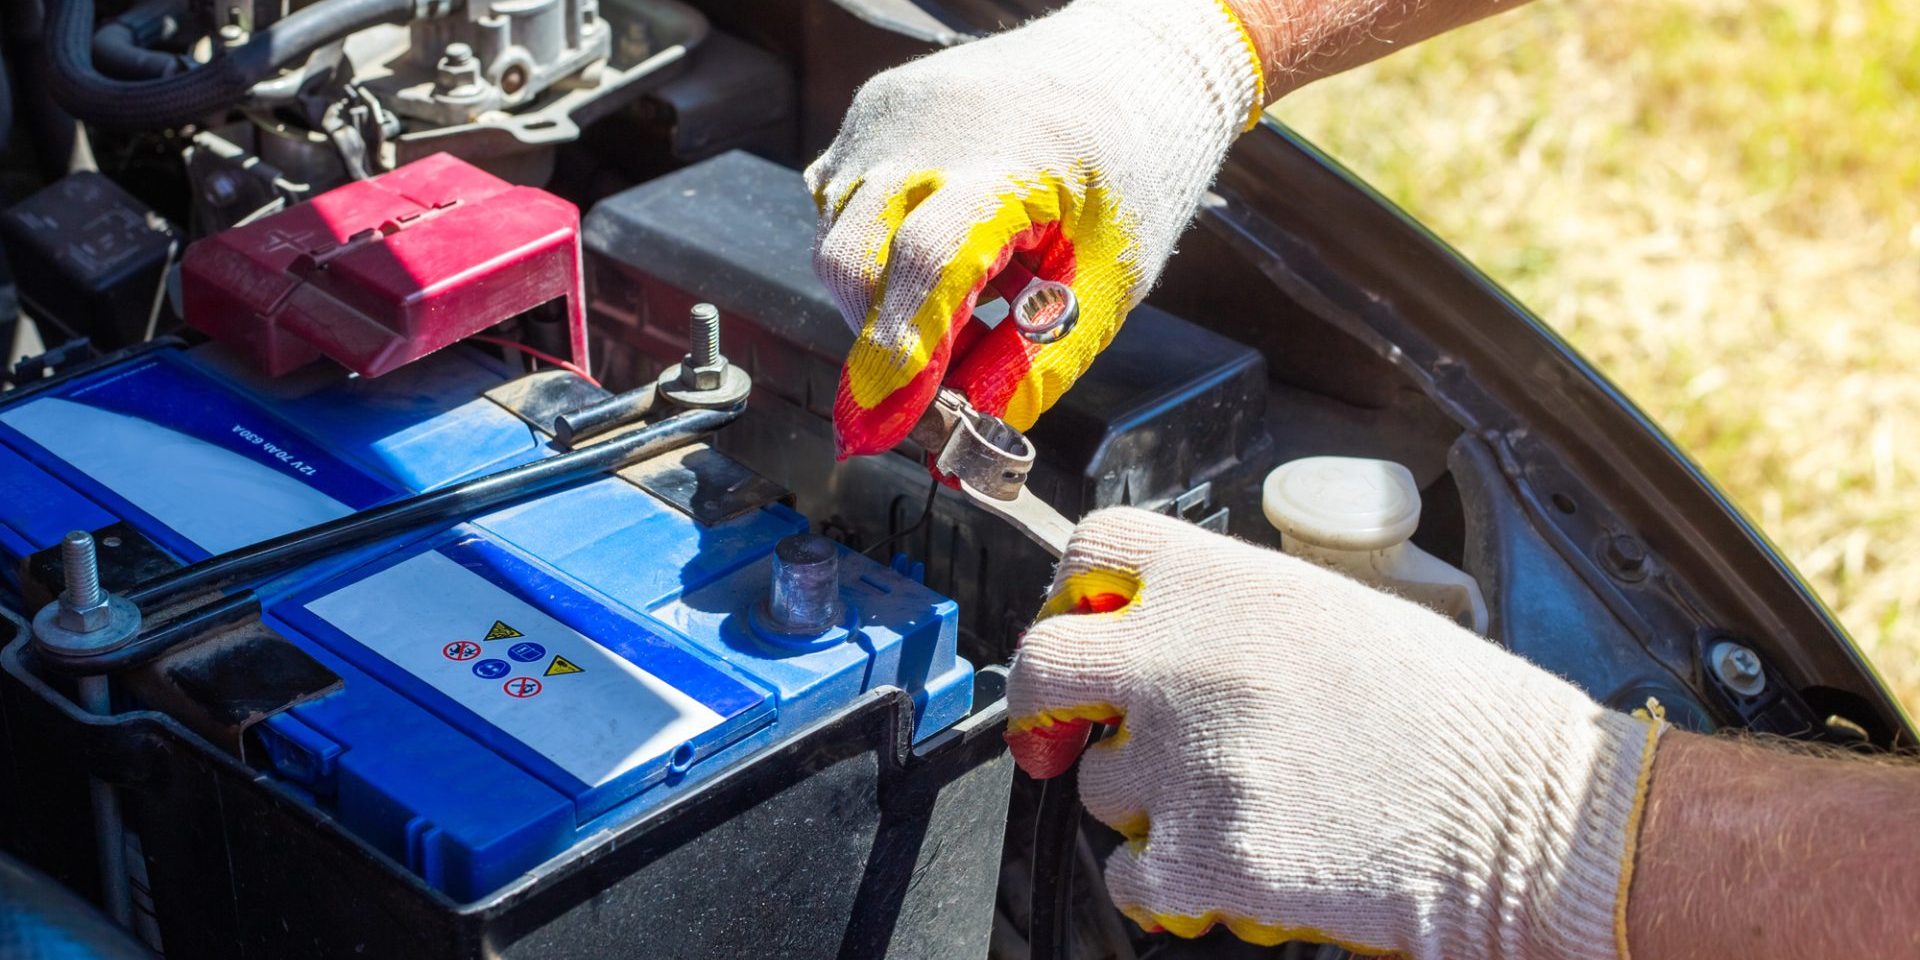
- The average car repair now runs about $838, and the Bureau of Labor Statistics says overall vehicle repair and maintenance costs have climbed 33% from 2021 levels.
- Gas is the cost drivers feel hardest and fastest, up 24.6% year over year in July, with AAA pricing the national average near $4.10 a gallon and a $2.17 gap between California and Indiana.
- There is one bright spot: auto insurance pricing has eased for six of the past seven months, even as claims themselves get more expensive to settle.
Your Insurance Bill Might Be Easing. Your Repair Bill Is Not.
A new analysis from ConsumerCoverage, released this month, lays out a split reality for American drivers heading into the fall. Gas and repair costs keep climbing. Auto insurance, after years of sharp increases, is finally cooling. Put those two trends next to each other and the result is a household budget that looks different than it did two years ago, even if the total dollar amount feels just as painful.
The clearest single number in the data is the price of getting your car fixed. The Bureau of Labor Statistics reports that repair and maintenance costs are up 6.6% over the past year alone, with repair work by itself up 6.2%. Zoom out further and the trend gets sharper: separate BLS figures compiled by ConsumerAffairs put the cumulative rise in repair and maintenance costs at 33% from 2021 levels, with the average repair bill now sitting around $838 for routine or moderate work, a figure Kelley Blue Book also cites as the current national average across all makes and models.
Why a Trip to the Shop Costs So Much More Than It Used To
Three forces are pushing repair bills up at once, and none of them is going away soon. The first is a shortage of qualified technicians. The industry needs roughly 258,000 new technicians to keep pace with demand, but only about 101,000 are projected to enter the field, and that gap pushes hourly labor rates higher as shops compete for fewer qualified hires.
The second is the car itself. Modern vehicles carry anywhere from 50 to 150 electronic control units running everything from fuel injection to climate control, plus cameras and radar sensors tied to driver-assist features. A fender bender that once meant a body shop visit now often means a camera recalibration too: even a small collision can knock a forward-facing sensor out of alignment. Parts and supply chain pressure make up the third piece, with component costs and availability both working against the driver’s wallet.
That repair inflation reaches beyond the shop bill itself. Insurers price policies around what they expect a claim to cost, so every dollar added to the average repair job puts upward pressure on premiums, even in months when the broader insurance market is calming down.
Gas Prices Do Not Wait for Anyone’s Budget
Gasoline is the cost that hits a household first: so little of it is optional. Gas prices were up 24.6% year over year in the July Consumer Price Index report, and AAA had the national average sitting near $4.10 a gallon in late August, with a wide split between states: $5.63 in California against $3.46 in Indiana, a gap of more than two dollars a gallon for the same commute.
The U.S. Energy Information Administration tracked weekly gasoline demand climbing from 8.68 million to 9.04 million barrels a day over that same stretch, evidence that higher prices are not pushing Americans to drive less. Commuting, school runs, and caregiving do not pause when the pump gets more expensive.
That burden does not land evenly. Bank of America Institute data cited in the analysis found lower-income households put about 4.2% of their income toward gas in March 2026, compared with 3.1% for higher earners, and one in ten lower-income households spent more than 10% of their income at the pump. A gas price spike that barely registers for one family can force another to cut spending elsewhere.
The One Line Item That Is Actually Getting Cheaper
Auto insurance tells a different story. The National Association of Insurance Commissioners put the average combined premium at $1,438 per vehicle in 2023, a 14.42% jump from the year before, with liability premiums climbing 19% between 2019 and 2023 while the number of insured vehicles grew just 5.5%. That run-up is part of why insurance became such a visible household expense over the past few years.
The latest BLS numbers show that trend reversing. The motor vehicle insurance index fell 4.5% year over year, including a 0.3% drop in July after a 2.0% decline in June, meaning the index has now fallen in six of the past seven months. Insurers are still absorbing higher claims costs from pricier repairs, but competition and softer claim frequency appear to be pulling overall pricing down even so.
How This Compares With a Few Years Ago
Put the numbers side by side and the shift in where a driver’s money goes becomes obvious. In 2023, insurance was the runaway cost, jumping more than 14% in a single year according to NAIC data, while repair inflation and gas prices, though elevated, were not moving at anywhere near that pace. Three years later, the order has flipped: insurance is easing off a multi-year high while gas and repair costs keep grinding upward, driven less by any single event and more by structural pressure that does not reverse quickly, a technician shortage, more complex vehicles, and global parts and commodity costs among them.
The practical effect for a household budget is that last year’s cost-cutting playbook, shopping around for a cheaper insurance policy, does not address this year’s biggest pressure points. A driver who successfully cut their insurance bill by switching carriers in 2024 or 2025 can still watch their total driving costs rise in 2026 purely from gas and repair inflation, even with a lower premium locked in.
The Regional Gap Behind the National Averages
Every figure in this analysis is a national average, and national averages flatten out real differences that matter to an individual household. A driver in California is paying gas prices more than two dollars a gallon higher than a driver in Indiana, and labor rates for a repair job in a high cost-of-living metro area routinely run well above the labor rates a shop in a small town charges for the identical job. Two households with the same car and the same driving habits can end up with meaningfully different annual costs purely based on ZIP code.
That regional spread is also why a single national repair average like $838 works best as a benchmark rather than a prediction. A driver whose most recent repair bill came in well above that figure is not necessarily being overcharged, and one whose bill came in well below it is not necessarily getting a bargain; local labor rates, parts availability, and the specific system that failed all move the number more than any national trend does.
What To Do
The Insurance Information Institute recommends comparing quotes across at least a few carriers rather than letting a policy auto-renew: rates are not moving uniformly, and last year’s best deal might not be this year’s. Drivers with an older vehicle should also revisit whether collision coverage and the separate policy that pays for theft, weather, and vandalism damage still make financial sense once the car’s value has dropped, given that those coverages can cost more annually than the payout would be worth after a total loss.
On the repair side, get a written estimate before authorizing work, and ask directly whether a job requires a sensor or camera recalibration, a step that adds cost easy to miss until the final bill arrives. Shopping around for routine maintenance, rather than defaulting to a dealer service department, can also narrow the gap between the national average repair bill and what a driver actually pays.
Sources:

Leave a Comment
More in News
How to Check if Your Jeep Wagoneer’s Roof Rack Is Part of a 97,000-Vehicle Recall
Volkswagen Recalls 208,724 SUVs Over Steering Bolts That Can Snap
Hyundai Recalls Ioniq 9 Over the Same Seat Defect That Killed a Toddler
How to Jump Start a Car Safely (and Avoid Damaging the Electronics)
What DVSA Data Reveals About the Postcodes With the Worst Driving Test Pass Rates
Trending on Motoring Chronicle
The artistry behind the Bugatti Baby II Tourbillon edition [Photo Gallery]
Small Cars and Sports Cars Have the Highest Driver Death Rates, IIHS Finds

Audi Concept C lights up London
What Illinois Drivers Over 79 Need to Know as Road Tests End July 1